Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Most Visited
  • Most Voted
  • Followed Questions
  • Most Answered
  • No Answers

AccountingQA Latest Questions

Aadil
AadilCurious
In: 1. Financial Accounting > Depreciation & Amortization

Total depreciation of an asset cannot exceed its?

book value replacement value depreciable value market value

Depreciation
  • 1 Answer
  • 0 Followers
Answer
  1. Vijay Curious M.Com
    Added an answer on July 20, 2021 at 2:11 pm
    This answer was edited.

    The total depreciation of an asset cannot exceed its 3. depreciable value.  Depreciable value means the original cost of the asset minus its residual/salvage value. The asset's original cost is inclusive of the purchase price and other expenses incurred to make the asset operational. To put it simplRead more

    The total depreciation of an asset cannot exceed its 3. depreciable value. 

    Depreciable value means the original cost of the asset minus its residual/salvage value. The asset’s original cost is inclusive of the purchase price and other expenses incurred to make the asset operational. To put it simply,

    The accumulated depreciation on an asset can never exceed its depreciable value because depreciation is a gradual fall in the value of an asset over its useful life. Only a certain percentage of the asset’s book value/original cost is shown as depreciation every year. So, it is impossible/illogical for the accumulated depreciation of an asset to exceed its depreciable value.

    Let me show you an example to make it more understandable,

    Amazon installs machines to automate the job of packing orders. The original cost of the machine is $1,000,000. Now let’s assume,

    The estimated useful life of the machine – 10 years.

    Residual value at the end of 10 years – $50,000.

    Method of depreciation – Straight-line method.

    The depreciable value of the machine will be $950,000 (1,000,000 – 50,000). The depreciation for each year under SLM will be calculated as follows:

    Depreciation = (Original cost of the asset – Residual/Salvage Value) / (Useful life of the asset)

    Applying this formula, $95,000 (1,000,000 – 50,000/10) will be charged as depreciation every year. The accumulated depreciation at the end of 10 years will be $950,000 (95,000*10). As you can see, the accumulated depreciation ($950,000) of the machine does not exceed its depreciable value ($950,000).

    Thus, the total depreciation of an asset cannot be more than its depreciable value.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Journal Entries

What is the journal entry for unbilled revenue?

  • 1 Answer
  • 0 Followers
Answer
  1. Vijay Curious M.Com
    Added an answer on August 5, 2021 at 2:17 pm
    This answer was edited.

    Sometimes a business may earn an income by delivering the goods/services within the stipulated time. But the business may not have issued an invoice to the customer. Such a scenario is what is called unbilled revenue. Note that as per the accrual concept of accounting, sales are recognized on the daRead more

    Sometimes a business may earn an income by delivering the goods/services within the stipulated time. But the business may not have issued an invoice to the customer. Such a scenario is what is called unbilled revenue.

    Note that as per the accrual concept of accounting, sales are recognized on the day it was made, irrespective of whether the business receives cash or not.

    The business records unbilled revenue by passing the following journal entry:
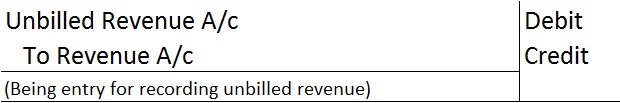
    Unbilled Revenue is treated as an asset because it is yet to be fully recognized as an income. Therefore it is debited. Revenue A/c is credited as there is an increase in income.

    Once the bill/invoice has been issued to the customer, the following entry is passed to close the Unbilled Revenue A/c.
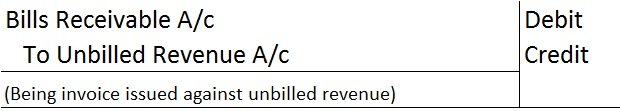
    Let me explain this concept with an example,

    Luca Traders, a business dealing in stationery and office supplies receives an order on August 5th for 1,000 pens worth 10 each. On August 8th they deliver the pens but they are yet to issue an invoice to the customer. They issue the invoice only on August 13th.

    So the sales revenue of 10,000 (1,000*10) will be treated as an unbilled revenue for the period of August 8th – August 12th. On August 8th the following entry is made to record unbilled revenue.

    Unbilled Revenue A/c  10,000
       To Revenue A/c  10,000
    (Being entry for recording unbilled revenue worth 10,000)

    When the invoice is sent to the customer on August 13th, the following journal entry is posted to close the unbilled revenue A/c.

    Bills Receivable A/c  10,000
       To Unbilled Revenue A/c  10,000
    (Being invoice issued against unbilled revenue)
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Depreciation & Amortization

What is a provision for depreciation account?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on October 4, 2021 at 7:46 pm
    This answer was edited.

    You must have knowledge of what depreciation is. Depreciation is the process of allocating the value of an asset over its useful life. It reduces the carrying value of the asset year by year till it is scraped. It is an expense (expense of using the asset for business purposes) and it is charged toRead more

    You must have knowledge of what depreciation is. Depreciation is the process of allocating the value of an asset over its useful life. It reduces the carrying value of the asset year by year till it is scraped.

    It is an expense (expense of using the asset for business purposes) and it is charged to profit and loss account.

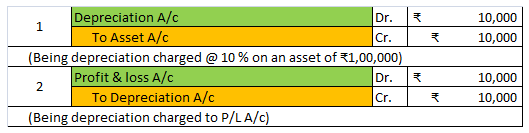
    Depreciation can be reported in the financial statement in two ways:

    1. Deduct depreciation from the asset account and show the asset at “depreciation less” value. See the journal entries below:

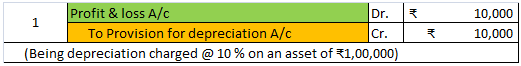
    1. Maintain a provision for depreciation account and show the asset account at original cost. In this method, no entry is passed through the asset account. See the journal entries below:


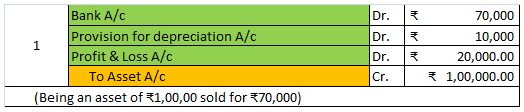
    Provision for depreciation account represents the collection of total depreciation till date on an asset. That’s why it is also called accumulated depreciation account. When an asset is sold, its accumulated depreciation is credited to the asset account. See the journal entry below:

    It is shown on the liabilities side of the balance sheet. It is a nominal account because it is shown as an expense in the statement of profit or loss.

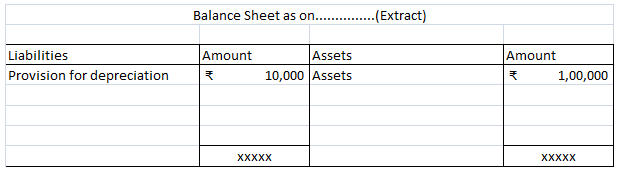
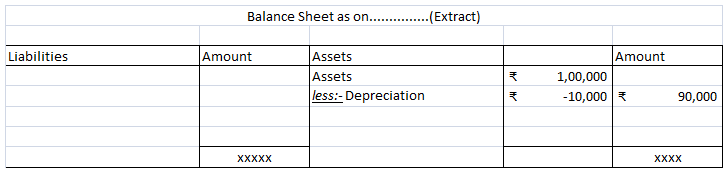
    In case provision for depreciation account is not maintained then the balance sheet looks like this:

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Miscellaneous

What is example of revenue reserve?

ReservesRevenue Reserve
  • 1 Answer
  • 0 Followers
Answer
  1. Rahul_Jose Aspiring CA currently doing Bcom
    Added an answer on November 15, 2021 at 3:18 pm
    This answer was edited.

    A revenue reserve is a type of reserve where a portion of the net profit is set aside for future requirements. It serves as a great source of internal finance for the company to meet its short term requirements. The funds put into this reserve are earned from the daily operations of a company. RevenRead more

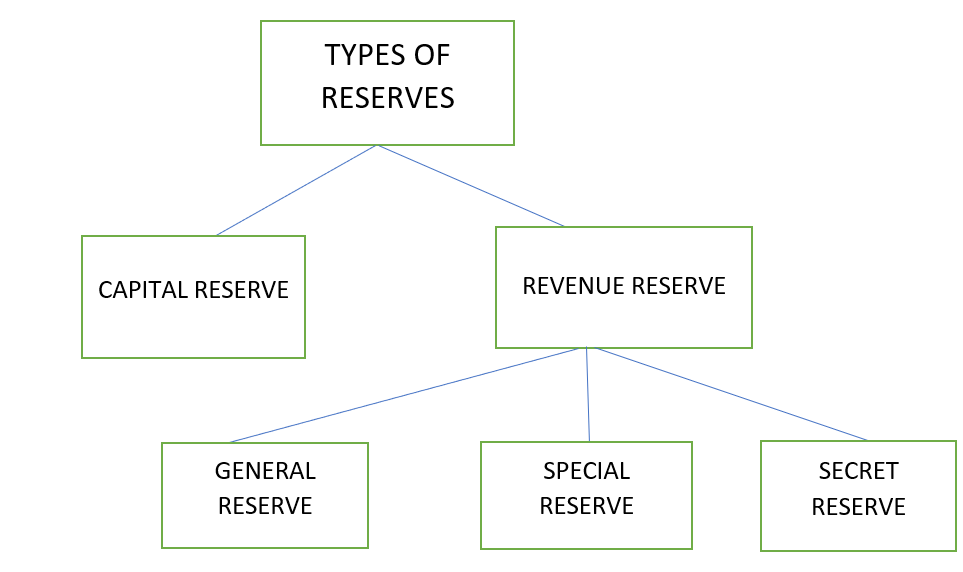
    A revenue reserve is a type of reserve where a portion of the net profit is set aside for future requirements. It serves as a great source of internal finance for the company to meet its short term requirements. The funds put into this reserve are earned from the daily operations of a company. Revenue reserves are shown on the liabilities side of a balance sheet under reserves and surplus. Some examples of revenue reserve are :

    • General Reserve: This reserve is used for no specific purpose, but the general financial growth of the company. It is a free reserve which means the company is not compelled to make one. It helps to curb future losses which may arise in the future.
    • Specific Reserve: These are those reserves that can only be used for specific purposes. This money cannot be used for any other requirement. It is not a free reserve. A reserve created to redeem debentures would be called a debenture redemption reserve.
    • Secret Reserve: This is a type of reserve whose existence is not disclosed in the balance sheet. This type of reserve cannot be created by joint-stock companies. However, banks and financial institutions are allowed to create such secret reserves.

    Retained Earnings is that part of the net profit which is left after the distribution of dividends to shareholders. This amount can be invested in the company to gain profits. It is not technically a reserve as it is held after distribution of dividends but it can still be used as one.

    On the other hand, a capital reserve is not a part of the revenue reserve. It is created from capital profits to finance long term projects of a company. It is used for specific purposes only.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Financial Statements

Balance Sheet discloses the financial position of a business

A. For a certain given period B. At a particular point of time C. After a fixed date D. None of the above

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on November 22, 2021 at 5:49 pm

    The correct option is Option (b) at a particular point of time. A balance sheet discloses the financial position of an entity at a particular point of time. The particular point of time is generally the last date of an accounting year. Most of the business concerns follow an accounting year ending oRead more

    The correct option is Option (b) at a particular point of time.

    A balance sheet discloses the financial position of an entity at a particular point of time. The particular point of time is generally the last date of an accounting year. Most of the business concerns follow an accounting year ending on 31st March and prepare their balance sheet as at 31st March.

    By financial position, it means the value of assets and liabilities of the entity. As an entity may enter into monetary transactions every day, the values of the assets and liabilities may also vary every day. Hence, to prepare the balance sheet of an entity, a particular point of time is to be chosen which is generally the last date of an accounting year

    Option (a) for a given period of time is incorrect.

    It is because the values of assets and liabilities of concern may differ daily, a balance sheet cannot be prepared to disclose the financial position of an entity for a given period of time.

    The statement of profit or loss is prepared for a given period of time as it discloses the overall performance of an entity for a given period of time.

    Option (c) after a fixed date is also incorrect.

    The phrase, “after a fixed date” does not indicate a particular point of time. It may mean any day after a fixed date. For example, if there is an instruction to prepare a balance sheet that discloses the financial position of a concern after 30th March, it may mean 31st March, 1st April or any day thereafter.

    As we know that a balance can be prepared for a particular point of time, this option seems wrong.

    Option (d) None of these is incorrect too as Option (b) is the correct one.

    See less
    • 1
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Astha
AsthaLeader
In: 1. Financial Accounting > Journal Entries

What is the journal entry for interest received from bank?

  • 1 Answer
  • 0 Followers
Answer
  1. Rahul_Jose Aspiring CA currently doing Bcom
    Added an answer on December 9, 2021 at 8:09 pm

    When a business deposits its money into a bank account, it receives a percentage of the amount deposited as bank interest. The journal entry for interest received from a bank is as follows: Since the Bank account is a current asset, it gets debited. This is in accordance with the modern rules of accRead more

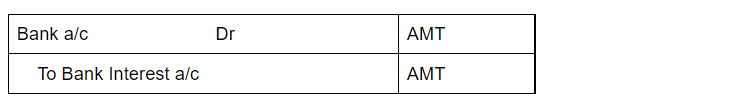
    When a business deposits its money into a bank account, it receives a percentage of the amount deposited as bank interest. The journal entry for interest received from a bank is as follows:

    Since the Bank account is a current asset, it gets debited. This is in accordance with the modern rules of accounting where an increase in assets is debited while a decrease in assets is credited. According to the traditional rules (golden rules) of accounting, a bank account is classified under Personal account with the rule of “debit the receiver” and “credit the giver”. In the given journal entry bank account is receiving money and is hence debited.

    Meanwhile, Bank interest is the income received by the business and according to the modern rule of accounting, an increase in incomes is credited and a decrease in incomes is debited. Whereas, considering the traditional rules (golden rules), bank interest comes under Nominal account where “all incomes are credited” and “all expenses are debited”. Therefore, considering these rules, bank interest is credited.

    EXAMPLE

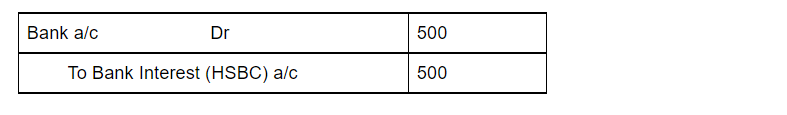
    If Gregor Ltd has a bank account with HSBC, having an opening balance of Rs 10,000 earning an interest of 5% per annum, then the journal entry for interest received from the bank is recorded as

    The interest amount is taken on the amount deposited in the bank (10,000 * 5%).

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
AbhishekBatabyal
AbhishekBatabyalHelpful
In: 1. Financial Accounting > Accounting Terms & Basics

What is the difference between operating lease and finance lease?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on June 24, 2022 at 6:40 pm
    This answer was edited.

    Meaning of lease A lease is an agreement or a contract in which the right to use an asset like land, building, or machinery is given by one party to the other party for a fixed period of time against the consideration of a single payment or a series of payments. There are two parties in a lease agreRead more

    Meaning of lease

    A lease is an agreement or a contract in which the right to use an asset like land, building, or machinery is given by one party to the other party for a fixed period of time against the consideration of a single payment or a series of payments.

    There are two parties in a lease agreement:

    • Lessor: The party who gives the right to use its asset in return for a series of payments or a single payment.
    • Lessee: The party who receives the right to use the asset from the Lessor.

    This is similar to a rent agreement or contract. The only difference between lease and rent is duration. A rent agreement is generally for less than 12 months while a lease agreement is for more than 12 months like 5 years or 10 years, sometimes even for like 99years.


    Type of lease

    There are two types of lease:

    • Operating lease
    • Finance Lease


    Operating lease

    • An operating lease is a type of lease in which the possession of the leased asset is transferred back from the lessee to the lessor at the end of the lease period.
    • Here, all the risk and rewards incident to ownership remains with the lessor, not the lessee.
    • The depreciation on the leased asset in case of operating lease is not charged by the lessee to its profit and loss account as the leased asset is not shown in the balance sheet. A leased asset is an off-balance sheet item in the case of an operating lease.


    Finance lease

    • Unlike an operating lease, the ownership of the leased asset is transferred to the lessee at the end of the leased period.
    • Thus, at the inception of the lease agreement, all the risk and rewards incident to ownership is transferred from the lessor to the lessee.
    • The depreciation on the leased asset is charged by the lessee to its profit and loss account as the leased asset is shown in the balance sheet. A leased asset is a balance sheet item in the case of an operating lease.
    • Along with the leased asset, the obligation to pay the future lease payment is also shown in the balance sheet as a non-current liability or current liability as the case may be.


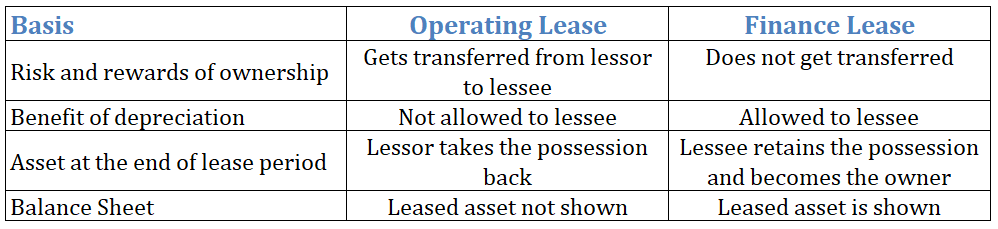
    Difference between operating lease and finance lease in tabular format


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Ledger & Trial Balance

What is the meaning of post to the ledger accounts?

  • 1 Answer
  • 0 Followers
Answer
  1. ShreyaSharma none
    Added an answer on August 10, 2022 at 12:53 pm
    This answer was edited.

    Ledger posting As we know, a business records all of its transactions in the journal. After the transactions are recorded in the journal, they are posted in the principal book called ‘Ledger’. Transferring the entries from journals to respective ledger accounts is called ledger posting or posting toRead more

    Ledger posting

    As we know, a business records all of its transactions in the journal. After the transactions are recorded in the journal, they are posted in the principal book called ‘Ledger’. Transferring the entries from journals to respective ledger accounts is called ledger posting or posting to the ledger accounts. Balancing of ledgers is carried out to find differences at the year’s end.

    Posting to the ledger account means entering information in the ledger, and respective accounts from the journal for individual records. The accounts that are credited are posted to the credit side and vice versa.

    Ledger maintenance is done at the end of an accounting period and it’s maintained to reflect a permanent summary of all the journal accounts. In the end, all the accounts that are entered and operated in the ledger are closed, totaled, and balanced. Balancing the ledger means finding the difference between the debit and credit amounts of a particular account.

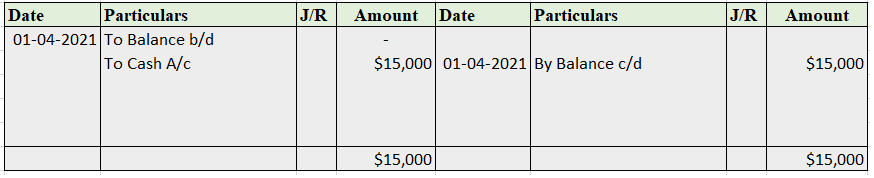
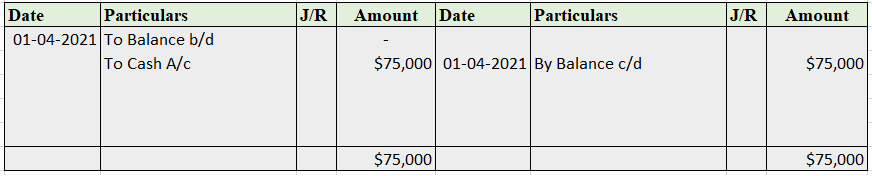
    While posting to the ledger account, suppose goods were bought for cash. While passing the journal entry, we’ll be debiting the purchases a/c and crediting the cash a/c by stating it as, ‘To Cash A/c’.

    Now, this entry will be affecting both the purchases account and the cash account. In the cash account, we’ll be debiting purchases. Whereas in the purchases account, we’ll be crediting the cash. That’s how it works in the double-entry bookkeeping system of accounting.

    Example

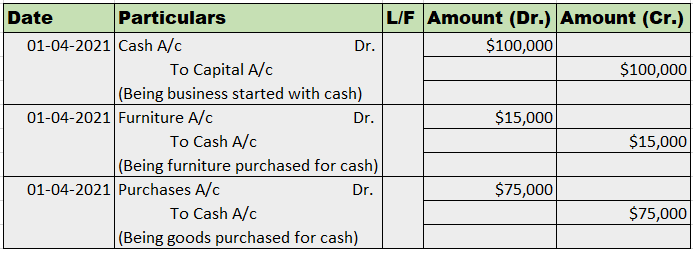
    Mr. Tony Stark started the business with cash of $100,000 on April 1, 2021. He bought furniture for business for $15,000. He further purchased goods for $75,000.

    Now, we’ll be journalizing the transactions and posting them into the ledger accounts.

    Journal Entries

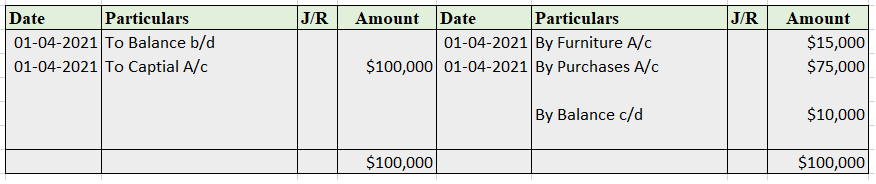
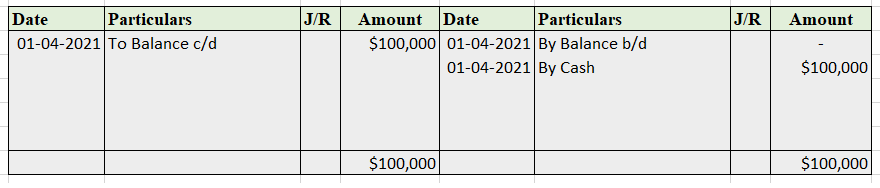
    Posting to Ledger Account

    Cash A/c

    Capital A/c

    Furniture A/c

    Purchases A/c


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Bonnie
BonnieCurious
In: 1. Financial Accounting > Ratios

What are profitability ratios?

  • 1 Answer
  • 0 Followers
Answer
  1. A_Team (MBA - Finance Student) ISB College
    Added an answer on December 13, 2022 at 5:28 am

    Profitability ratios measure how profitable a company is and are used to assess its performance and efficiency. Based on the income statement and balance sheet of a company, these ratios are calculated. In terms of profitability ratios, there are several types, each providing a different viewpoint.Read more

    Profitability ratios measure how profitable a company is and are used to assess its performance and efficiency. Based on the income statement and balance sheet of a company, these ratios are calculated.

    In terms of profitability ratios, there are several types, each providing a different viewpoint.

    The following are some common profitability ratios:

    Gross profit margin: This ratio measures the percentage of revenue that remains after the cost of goods sold has been deducted. Producing and selling efficiently is indicated by this metric.

    Net profit margin: An organization’s net profit margin is the portion of revenue left after all expenses have been deducted. A company’s profitability is measured by this indicator.

    Return on assets (ROA): This ratio measures how profitable a company’s assets are. In other words, it indicates how effectively a company generates profits from its assets.

    Return on equity (ROE): This ratio measures the profitability of a company’s equity. It shows how effectively a company generates profits from its shareholders’ investments.

    Analysts and investors use profitability ratios to evaluate a company’s performance and profitability ability.

    An investor or analyst can evaluate a company’s relative strength and identify potential opportunities or risks by comparing its profitability ratios with its peers or its industry averages.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Ledger & Trial Balance

what does a trial balance include?

  • 1 Answer
  • 4 Followers
Answer
  1. Ishika Pandey Curious ca aspirant
    Added an answer on February 14, 2023 at 2:55 am
    This answer was edited.

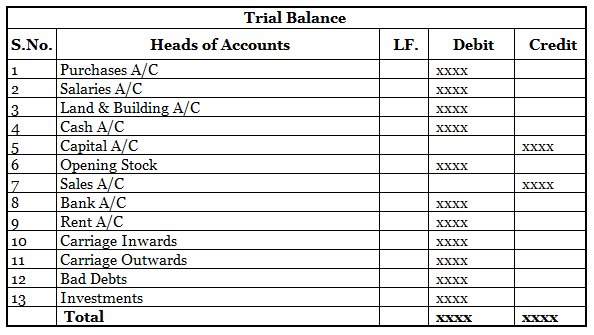
    Definition The trial balance is a list of all the closing balances of the general ledger at the end of the year. Or in other words, I can say that it is a statement showing debit and credit balances. A trial balance is prepared on a particular date and not on a particular period. What does trial balRead more

    Definition

    The trial balance is a list of all the closing balances of the general ledger at the end of the year. Or in other words, I can say that it is a statement showing debit and credit balances.

    A trial balance is prepared on a particular date and not on a particular period.

    What does trial balance include?

    As in each double-entry system, each account has two aspects debit and credit.

    Hence the following trial balance includes:
    • Debit or credit of the reporting period.
    • The amount which is to be debited or credited to each account.
    • The account numbers.
    • The dates of the reporting period.
    • The totaled sums of debits and credits entered during that time.

    When we prepare a trial balance from the given list of ledger balances, these need to be included which are as follows :

    The balance of all
    • Assets accounts
    • Expenses accounts
    • Losses
    • Drawings
    • Cash and bank balances
    Are placed in the debit column of the trial balance.

    • The balances of
    • liabilities accounts
    • income accounts
    • profits
    • capital
    Are placed in the credit column of the trial balance.

    Importance

    As the trial balance is prepared at the end of the year so it is important for the preparation of financial statements like balance sheets or profit and loss.

    The purpose of the trial balance is as follows:

    • To verify the arithmetical accuracy of the ledger accounts
    This means trial balance indicates that equal debits and credits have been recorded in the ledger accounts.
    It enables one to establish whether the posting and other accounting processes have been carried out without any arithmetical errors.

    • To help in locating errors
    There can be some errors if the trial balance is untallied therefore to get error-free financial statements trial balance is prepared.

    • To facilitate the preparation of financial statements
    A trial balance helps us to directly prepare the financial statements and then which gives us the right to not look or no need to refer to the ledger accounts.

    Structure of trial balance

    See less
    • 10
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.