Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Most Visited
  • Most Voted
  • Followed Questions
  • Most Answered
  • No Answers

AccountingQA Latest Questions

Radha
Radha
In: 1. Financial Accounting > Accounting Terms & Basics

Who are internal users of accounting information?

Internal Users
  • 1 Answer
  • 0 Followers
Answer
  1. Vijay Curious M.Com
    Added an answer on July 8, 2021 at 4:35 pm
    This answer was edited.

    One of the main purposes of accounting is to provide financial data to its users so that decisions are taken at an appropriate time. These users of accounting information are broadly classified into (a) internal users and (b) external users. Since the question concentrates on internal users I’ll beRead more

    One of the main purposes of accounting is to provide financial data to its users so that decisions are taken at an appropriate time. These users of accounting information are broadly classified into (a) internal users and (b) external users. Since the question concentrates on internal users I’ll be explaining internal users of accounting information in detail.

    Internal users are people within an organization/business who need accounting information to make day-to-day decisions.

    The various internal users of accounting information include:

    • Owners/Promoters/Directors:

    Owners are the people who contribute capital to the business and therefore they are interested to know the profit earned or loss incurred by the business as well as the safety of their capital. In the case of a Sole Proprietorship, the proprietor is the owner of the business. In the case of a Partnership, the partners are considered as the owners of the firm.

    The use for them: To know how the business is doing financially, owners need to know the profit and loss reflected in the financial statements.

    • Management:

    Management is responsible for setting objectives, formulating plans, taking informed decisions, and ensuring that pre-planned objectives are met within the stipulated time period.

    The use for them: To achieve objectives, management needs accounting information to make decisions related to determining the selling price, budgeting, cost control and reduction, investing in new projects, trend analysis, forecasting, etc.

    • Employees/Workers:

    Employees and workers are the ones who implement the plans set by the management. Their well-being is dependent on the profitability of the business.

    The use for them: They are interested to check the financial statements so that they can get a better knowledge of the business. Some organizations also give their employees a share in their profits in the form of a bonus at the year-end. This also creates an interest in the employees to check the financial statements.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Miscellaneous

What are some examples of fictitious asset?

  • 1 Answer
  • 0 Followers
Answer
  1. Vijay Curious M.Com
    Added an answer on July 28, 2021 at 2:40 pm
    This answer was edited.

    Fictitious assets are not actually assets. They are expenses/losses not written off in the year in which they are incurred. They do not have any physical presence. Their expense is spread over more than one accounting period. A part of the expense is amortized/written off every year against the compRead more

    Fictitious assets are not actually assets. They are expenses/losses not written off in the year in which they are incurred. They do not have any physical presence. Their expense is spread over more than one accounting period.

    A part of the expense is amortized/written off every year against the company’s earnings. The remaining part (which is yet to be written off) is shown as an asset in the balance sheet. They are shown as assets because these expenses are expected to give returns to the company over a period of time.

    Here are some examples of fictitious assets:

    • Preliminary expenses.
    • Promotional expenses.
    • Loss incurred on the issue of debentures.
    • Underwriting commission.
    • Discount on issue of shares.


    To make it simple I’ll explain the accounting treatment of preliminary expenses with an example.

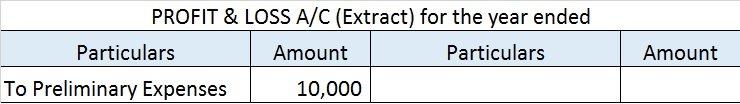
    The promoters of KL Ltd. paid 50,000 as consultation fees for incorporating the company. The consultation fee is a preliminary expense as they are incurred for the formation of the company. The company agreed to write off this expense over a period of 5 years.

    At the end of every year, the company will write off 10,000 (50,000/5) as an expense in the Profit & Loss A/c.

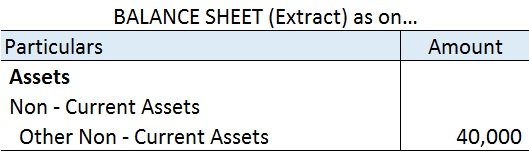
    The remaining portion i.e. 40,000 (50,000 – 10,000) will be shown on the Assets side of the Balance Sheet under the head Non – Current Assets and sub-head Other Non – Current Assets. 

    Here are the financial statements of KL Ltd.,
    Note: As per AS 26 preliminary expenses are fully written off in the year they are incurred. This is because such expenses do not meet the definition of assets and must be written off in the year of incurring.

    Source: Some fictitious assets examples are from Accountingcapital.com & others from Wikipedia.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Naina@123
Naina@123
In: 1. Financial Accounting > Miscellaneous

What is the difference between cash discount & trade discount?

  • 1 Answer
  • 0 Followers
Answer
  1. prashant06 B.com, CMA pursuing
    Added an answer on August 18, 2021 at 4:41 pm

    A cash discount is a discount allowed to customers when they make payments for the items they purchased. This type of discount is generally based on time. The early the payment is made by the debtors, the more discount they earn. To be more precise cash discount is given to simulate or encourage earRead more

    A cash discount is a discount allowed to customers when they make payments for the items they purchased. This type of discount is generally based on time. The early the payment is made by the debtors, the more discount they earn. To be more precise cash discount is given to simulate or encourage early payment by the debtors.

    Trade discount is a discount allowed by traders on the list price of the goods to the customer at specified rate. Unlike cash discount, trade discount is based on number of sale i.e, more the sale more the discount earned. This is mainly given on bulk orders by the customers.

    To understand trade discount and cash discount let me give you simple example

    Mr. X purchased goods from Mr. Y of list price Rs 10,000. Mr. Y allowed a 10% discount to Mr.X on the list price for purchasing goods in bulk quantity. Further, he was provided with cash discount of Rs 500 for making an immediate payment. Therefore the entry for the above transaction in the books of Mr. X would be

    Purchase A/c                                                        ……Dr 9,000
               To Cash A/c 8,500
               To Discount received 500
    (Being goods purchased from Mr. Y worth Rs. 10,000@ 10% trade discount and cash discount of Rs. 500)
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Manvi
Manvi
In: 1. Financial Accounting > Partnerships

What are unrecorded liabilities?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on October 19, 2021 at 3:03 pm
    This answer was edited.

    As the name suggests, unrecorded liabilities means the liabilities that a firm fails to record in its book of accounts. Usually, a firm gets to know about its unrecorded liabilities when it is about to get dissolved. What happens is that upon hearing that a firm is going to dissolve in near future,Read more

    As the name suggests, unrecorded liabilities means the liabilities that a firm fails to record in its book of accounts.

    Usually, a firm gets to know about its unrecorded liabilities when it is about to get dissolved. What happens is that upon hearing that a firm is going to dissolve in near future, its creditors and lenders report to the firm about their dues.

    At that time, a firm may get to know that it had failed to record some liabilities in its books and it has settled them now.

    We know that when a partnership firm is dissolved, a realisation account is created to which all the assets and liabilities of the firm are transferred.  Entries are as given below:

    Realisation A/c     Dr.      ₹ Amt

    To Assets A/c                  ₹ Amt

    ( Asset transferred to realisation account)

    Liabilities A/c    Dr.        ₹ Amt

    To Realisation A/c       ₹ Amt

    (Liabilities transferred to realisation account)

    Hence, for transferring unrecorded liabilities, the procedure is the same for the recorded liabilities:

    Unrecorded Liabilities A/c        Dr.     ₹ Amt

    To Realisation A/c                               ₹ Amt

    ( Unrecorded liabilities transferred to realisation account)

    Then to pay off the unrecorded liability the entry is:

    Realisation A/c     Dr.    ₹ Amt

    To Cash / Bank A/c       ₹ Amt

    (Unrecorded liabilities paid off)

    That’s it, I hope I was able to make you understand.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Ayushi
AyushiCurious
In: 1. Financial Accounting > Financial Statements

Can a company pay managerial remuneration in case of inadequate profit or loss?

  • 1 Answer
  • 0 Followers
Answer
  1. Rahul_Jose Aspiring CA currently doing Bcom
    Added an answer on November 25, 2021 at 6:28 pm
    This answer was edited.

    When a manager provides services to a company, he is expected to receive some kind of compensation. This is given in the form of managerial remuneration. Section 197 of the Companies Act allows a maximum remuneration of 11% of the net profit of the company to the directors, managing directors and whRead more

    When a manager provides services to a company, he is expected to receive some kind of compensation. This is given in the form of managerial remuneration. Section 197 of the Companies Act allows a maximum remuneration of 11% of the net profit of the company to the directors, managing directors and whole-time directors etc. This section is applicable for public companies and not private companies

    Yes, a company can pay managerial remuneration in case of inadequacy of profits or losses, provided they follow the condition in Schedule V of the Companies Act 2013.

    Conditions

    In order to pay remuneration while the company is at a loss, it has to comply with the following:

    • Pass a resolution at the board meeting
    • The company has not defaulted in payments to any Banks, non-convertible debenture holders or any secured creditors. But in case of default, the company has obtained prior approval from such creditors or banks before obtaining approval from their general meeting.
    • Ordinary resolution or special resolution (if the limit is exceeded)

    The limit mentioned above refers to the maximum limit of Rs 60 lakhs when the effective capital is negative or less than Rs 5 Crore. Such remuneration can also only be paid if such a manager does not have any interest in the company and also possesses special knowledge and expertise along with a graduate-level qualification.

    Effective capital is the aggregate of paid-up share capital, share premium, reserves and surplus, long term loans and deposits and after subtracting Investments, accumulated losses and preliminary expenses not written off.

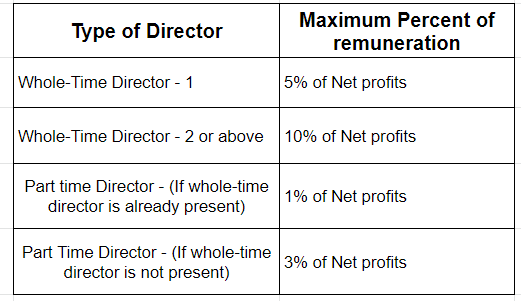
    Percentage of Remuneration

    When the Company earns adequate profits, they are allowed to provide remuneration up to a certain per cent. The percentage of remuneration depends on whether the directors are working whole-time or part-time according to the Companies Act.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Aadil
AadilCurious
In: 1. Financial Accounting > Financial Statements

What is the treatment of general reserve in cash flow statement?

  • 1 Answer
  • 0 Followers
Answer
  1. Pooja_Parikh Aspiring Chartered Accountant
    Added an answer on December 21, 2021 at 6:10 pm
    This answer was edited.

    A cash flow statement presents the changes in the cash and cash equivalents of a business. It classifies the cash flow items into either operating, investing, or financing activities. The cash flow statement provides information about the flow of cash over a period of time. General reserve is a reseRead more

    A cash flow statement presents the changes in the cash and cash equivalents of a business. It classifies the cash flow items into either operating, investing, or financing activities. The cash flow statement provides information about the flow of cash over a period of time.

    General reserve is a reserve created by taking a portion of the profits for future requirements.

    TREATMENT OF GENERAL RESERVE

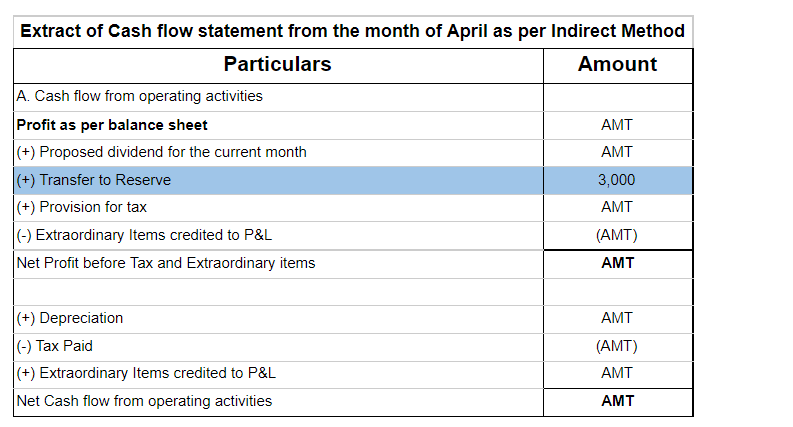
    As per the indirect method, Since there is no actual flow of cash, any addition to reserves is added back to net profit for calculation of net profit before tax and extraordinary items. This net profit before tax will appear under cash flow from operating activities. If there is a reduction in reserve, then they are subtracted from net profit.

    As per the Direct method, an increase or decrease in general reserve will not affect the cash flow statement since non-cash items are not recorded. Only cash receipts and payments that come under operating activities are recorded. So, net profit is not shown in the direct method and hence neither is general reserve.

    General reserve does not fall under the head investing activities as investing activities involve the acquisition or disposal of long-term assets or investments. They do not fit in financing activities either as financing activities relate to change in capital or borrowings of the company.

    EXAMPLE

    If the balance in general reserve for the period of March was Rs 4,000 and in April the balance was Rs 7,000, then its treatment in cash flow would be:


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Journal Entries

What is furniture journal entry?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on July 22, 2022 at 5:59 pm
    This answer was edited.

    Introduction   Furniture is treated as a fixed asset of an enterprise unless it deals in the manufacturing or the trade of furniture. As stock in trade, it will be treated as current assets. In both cases, they are real accounts. Hence, the golden rule of accounting will be the same. But, when it coRead more

    Introduction


    Furniture is treated as a fixed asset of an enterprise unless it deals in the manufacturing or the trade of furniture. As stock in trade, it will be treated as current assets.

    In both cases, they are real accounts. Hence, the golden rule of accounting will be the same.

    But, when it comes to journal entries, Furniture A/c will appear only when it is treated as a fixed asset.

    No journal entries are passed in the stock-in-trade account except for some balance transferring entries.

    Journal Entries on taking Furniture as a fixed asset

    Taking furniture as a fixed asset, we can pass various entries related to it. Since furniture is an asset, any increase is debited and the decrease is credited.

    Also, furniture is a real account which means the golden rule of accounting  applicable is, “Debit what comes in and credit what goes out”.

    Following are the basic entries related to furniture.

    Purchase of furniture

    The most common entry related to furniture is the purchase of furniture:

    Furniture A/c                                            Dr. Amt
    To Cash / Bank A/c Amt

    Here Furniture A/c is increased, hence debited.
    Cash or Bank being reduced is credited.

    Sale of furniture


    Cash / Bank A/c                                       Dr. Amt
    Profit and Loss A/c *                               Dr. Amt
    To Furniture A/c Amt
    To Profit and Loss A/c  ** Amt

     *In case of loss

    **In case of profit

     On the sale of furniture, its balance gets reduced, hence credited.
    Cash or Bank is debited as cash comes in hand or into the bank.

    Also, profit or loss may arise due to the difference in sale value and the carrying amount of the furniture A/c.

    The difference is debited to Profit and Loss A/c in case of loss and credited in case of profit.


    Depreciation on Furniture

    Depreciation A/c                                         Dr. Amt
    To Furniture A/c Amt

    Here, furniture is credited as it is decreased by the amount of depreciation.

    Depreciation being a non-cash expense, is debited.

    Journal Entries on taking Furniture as stock in trade

    When furniture is stock of trade of a business, the journal entries will be like normal purchase and sales entries as below:


    Purchase A/c                                               Dr. Amt
    To Cash / Bank A/c Amt


    Cash / Bank A/c                                          Dr. Amt
    To Sales A/c Amt

    There will be no furniture account.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Subsidiary Books

Can someone share petty cash book format?

  • 1 Answer
  • 0 Followers
Answer
  1. ShreyaSharma none
    Added an answer on August 27, 2022 at 10:52 pm
    This answer was edited.

    Introduction & Definition Firstly, let's see what the term 'petty cash book' means. The word ‘petty’ means small. A petty cash book is identical to a cash book, maintained to record the small expenses of a business like stationery, postage, stamps, carriage, etc. The cash received by a petty casRead more

    Introduction & Definition

    Firstly, let’s see what the term ‘petty cash book’ means. The word ‘petty’ means small. A petty cash book is identical to a cash book, maintained to record the small expenses of a business like stationery, postage, stamps, carriage, etc. The cash received by a petty cashier is recorded on the debit/ receipt side whereas, the money he pays is recorded on the credit/ payment side. The difference between the sum of the debit and credit items represents the balance of the petty cash in hand.

    The reason the petty cash book is maintained is that it records small expenses that are inconvenient or too small to be registered in the cash book. This is also called a simple petty cash book. Just like a cash book is maintained by the accountant, the petty cash book is maintained by a petty cashier.

    When it comes to the format, there are two types of petty cash book formats. They are-

    1. Simple Petty Cash Book
    2. Analytical Petty Cash Book

    We have been discussing the simple petty cash book so far. Thus,

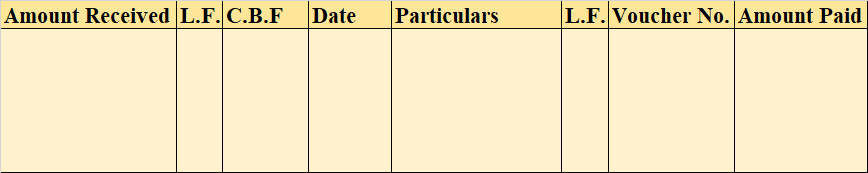
    Format of Simple Petty Cash Book


    Analytical Petty Cash Book

    The analytical petty cash book has numerous columns for the recording of monetary transactions. In the analytical petty cash book, there are pre-existing columns for the usual expenses that are recorded frequently in the business which makes it easier for a business that has daily expenses for food, stationery, postage, etc. They’ll be having individual columns. It has numerous columns in it for the recording of expenses in it.

    The key advantages of an analytical petty cash book are-

    • One of the major key advantages is that the analytical petty cash book due to its format and structure saves time.
    • The other advantage is that it helps the business in easy comparisons.
    • It requires lesser time in recording.


    Format of Analytical Petty Cash Book


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Miscellaneous

Which of these is a fictitious Asset?

Goodwill Patents Preliminary Expense A/c Claims Receivable

  • 1 Answer
  • 0 Followers
Answer
  1. Karishma
    Added an answer on September 25, 2023 at 1:01 pm
    This answer was edited.

    Fictitious assets are expenses or losses not written off entirely in the profit and loss account during the accounting year in which they occur. Fictitious assets have no realizable value or physical existence. In the above, (C) preliminary expense is a fictitious asset. Preliminary expenses are theRead more

    Fictitious assets are expenses or losses not written off entirely in the profit and loss account during the accounting year in which they occur. Fictitious assets have no realizable value or physical existence.

    In the above, (C) preliminary expense is a fictitious asset. Preliminary expenses are the expenses incurred before the incorporation of a business. The word ‘fictitious’ means fake, these are not actually the assets of a company even though they are represented in the assets of the balance sheet.

    Since the benefit of a fictitious asset is received over a period of time, the whole amount is not charged to the profit and loss account. The amount is amortized over several years. These expenses are non-recurring in nature. These expenses are shown as assets under the head miscellaneous expenditure. Also known as deferred revenue expenditure.


    For example: A company incurred $50,000 as promotion costs before the formation of the business. This promotion cost will be deferred over 5 years. In the first year, $10,000 will be charged to the profit and loss account and the remaining $40,000 will be shown as an asset under the heading miscellaneous expenditure. Subsequently, $10000 will be charged to profit and loss for the next 4 years. The amount of $50,000 will be deferred over a span of 5 years.

    Some other examples of fictitious assets :

    • Promotional expenses: Expenses incurred for the promotion of business before the formation of the company such as advertising expenditures are amortized over many years.
    • Loss on the issue of shares or debentures: When a company issues shares or debentures at a discount, the discount is classified as a fictitious asset and is not treated as an expense or loss. It is amortized over several years.
    • Incorporation costs: Costs incurred during the formation of a business are incorporation costs. These include registration costs, licensing fees, legal fees and other costs incurred in setting up the business. These are fictitious assets and are amortized over several years.
    • Loss on Sale of Machinery: When a loss is incurred on the sale of machinery or equipment, that loss is also treated as a fictitious asset and is amortized over several years.


    Goodwill

    Goodwill is not a fictitious asset because goodwill has a realizable value and can be sold in the market. Goodwill is an intangible asset which does not have a physical existence but can be traded for monetary value. Goodwill has an indefinite life and is sold when the business is sold. Goodwill can be self-generated or purchased. Goodwill is shown as an intangible asset under the heading fixed asset in the financial statements.


    Patents

    Patents are intangible assets which do not have a physical existence but have realizable value and can be sold in the market. So, patents do not come under the category of fictitious assets. Patents are basically intellectual property. The purchase price of the patent is the initial purchase cost which is amortized over the useful life of the asset. Patents are shown as intangible assets under the heading fixed asset in the balance sheet of the company.


    Claim receivable

    Claim receivable is an asset if the claim has been authorized by the insurance company. Claim receivable has a monetary value, so does not come under the category of a fictitious asset. If the claim is not yet authorized by an insurance company, it will be shown as a footnote in the financial statements. Authorized claim receivable is shown as a current asset in the financial statement.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Depreciation & Amortization

Difference between Amortization & Impairment?

AmortizationDifference BetweenImpairment
  • 1 Answer
  • 0 Followers
Answer
  1. Astha Leader Pursuing CA, BCom (Hons.)
    Added an answer on June 12, 2021 at 2:49 pm
    This answer was edited.

    Let us first understand the concepts of Amortization and Impairment. Amortization refers to the expense recorded on the decline of the value of intangible assets of a company. Intangible assets include goodwill, patents, copyrights, etc. It reflects the reduction in the value of Intangible assets ovRead more

    Let us first understand the concepts of Amortization and Impairment.

    Amortization refers to the expense recorded on the decline of the value of intangible assets of a company. Intangible assets include goodwill, patents, copyrights, etc. It reflects the reduction in the value of Intangible assets over its life span.

    Amortization is similar to Depreciation, however, while depreciation is over tangible assets amortization is over Intangible assets of the company.

    For example, Cipla Ltd. acquired a patent over a new drug for a period of 10 years. The cost of creating the new drug was 80,000 and the company must record its patent at 80,000. However, the company must amortize this cost by dividing the cost over the patent’s life, i.e., the amortization cost would be 8,000 (80,000/10) p.a. for the next 10 years.

    Impairment means a decline in the value of fixed assets due to unforeseen circumstances. Assets are impaired when the carrying value of assets increases its market value or “realizable value” and such increase is recorded as an impairment loss.

    Now suppose, Cipla Ltd. had existing machinery which suffered physical damage and is recorded at 50,000 in the books but the realizable value of the asset would only be 20,000. Hence, the asset would be written down to 20,000 and an impairment loss of 30,000 will be recorded.

    Impairment Vs Amortization

    Differences between the two can be shown as follows:

    Amortization Impairment
    Amortization is a reduction in the value of Intangible Assets over their useful life. Impairment is a reduction in the value of assets due to unforeseen circumstances.
    Amortization is a continuous process and the value of an asset reduces over time. Value of asset reduces drastically, creating a need to write down the value to its fair market value.
    Amortization is charged annually. Impairment is not an annual charge.
    Amortization is shown as an amortization expense. Impairment is shown as an impairment loss.
    Reasons for amortization includes consumption, obsolescence, etc. Reasons for impairment include damage to the asset, change in preferences, etc.
    Amortization is charged on Intangible assets Impairment is charged on fixed assets whether tangible or intangible.

    Suppose Unilever Ltd. has a patent over one of its products for a period of 5 years. The cost of the patent was 1,00,000. Then after 2 years one of its rivals, say ITC Ltd., launches a new product which is more preferred by the consumers over the one produced by Unilever Ltd. and the fair market value of the patent of Unilever Ltd. changes to 10,000.

    Now in this scenario, Unilever Ltd. would have amortized the patent (costing 1,00,000) at 20,000 (1,00,000/5) p.a. for 2 years and the book value at the end of the 2nd year is 60,000 (1,00,000 – 40,000). Now due to the new launch by ITC Ltd. the drastic change in the value of the asset from the book value of 60,000 to the realizable value of 10,000 will be recorded as an Impairment loss. Hence Impairment loss would be recorded at 50,000 (60,000 – 10,000).

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.