Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Most Visited
  • Most Voted
  • Followed Questions
  • Most Answered
  • No Answers

AccountingQA Latest Questions

AbhishekBatabyal
AbhishekBatabyalHelpful
In: 1. Financial Accounting > Depreciation & Amortization

What is mobile phone depreciation rate?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on December 20, 2021 at 7:18 pm

    Today, mobile phones especially smartphones are an indispensable part of most businesses and they qualify as fixed assets as they usually last for more than a year. Being a fixed asset, the depreciation on mobile phones is to be provided. The rate of depreciation to be charged on mobile phones is 15Read more

    Today, mobile phones especially smartphones are an indispensable part of most businesses and they qualify as fixed assets as they usually last for more than a year. Being a fixed asset, the depreciation on mobile phones is to be provided.

    The rate of depreciation to be charged on mobile phones is 15% WDV* as per the Income Tax Act. The rates as per the companies act, 2013 are 4.75% SLM** and 13.91% WDV*.

    *Written Down Value **Straight Line Method

    A company has to charge depreciation on mobiles in their books as per the rates of Companies Act, 2013.

    Any business or entity other than a company can choose the rate as per the Income Tax Act, 1961 which is 15% WDV. It is a general practice for non-corporates to charge depreciation in their books as per the rates of the Income Tax Act.

    An important thing to know is that as per the Income Tax Act, 1961, mobile phones are treated as plants and machinery and the general rate of 15% is applied to it.

    One may consider mobile phones as computers and charge depreciation at the rate of 40%. However, such a practice is not correct. Mobile phones are not considered equivalent to computers and there is case judgment given by Madras High Court which backs this consideration. The case is of Federal Bank Ltd. vs. ACIT (supra).

    Therefore we are bound to this case judgment and should treat mobile phones as part of plant and machinery and charge depreciation on it accordingly for the time being.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Partnerships

How to treat workmen compensation claim in revaluation account?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on August 13, 2022 at 9:29 am

    Meaning of Workmen's Compensation Reserve Workmen compensation reserve is a reserve created to compensate the labourers and employees of a firm in case of an uncertain future event in the line with their work. For example, if a labourer or group of labourers get injured seriously while working on thRead more

    Meaning of Workmen’s Compensation Reserve

    Workmen compensation reserve is a reserve created to compensate the labourers and employees of a firm in case of an uncertain future event in the line with their work. For example, if a labourer or group of labourers get injured seriously while working on the premises of the firm, then they will be compensated from the money kept aside in the workmen’s compensation reserve.

    Workmen’s compensation reserve is created using the profits of a business. The journal entry for the creation of workmen compensation reserve is as follows:
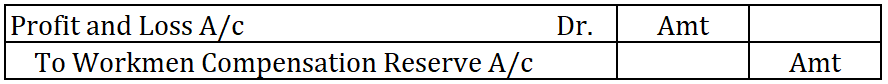
    When a claim arises, the claim amount is transferred to Provision for workmen compensation claim A/c

    Treatment of workmen compensation reserve in revaluation account

    At the time of admission, retirement or death of partner or change in profit sharing ratio, the reserve is distributed among the old or existing partners or kept intact.

    Workmen’s compensation reserve is also distributed among the old or existing partners subject to the claim arising on the reserve.

    Here are the three situations:
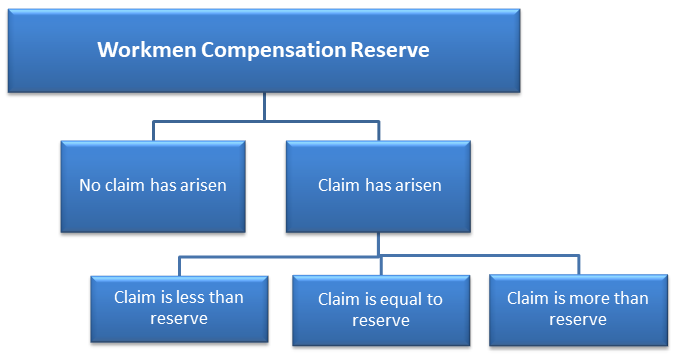
     

    The revaluation account comes into the picture only when the claim is more than the amount available in the reserve. For example, the claim is Rs. 20,000 but the amount in the reserve is only Rs. 15,000.

    In such a case, the excess claim will be met by debiting the revaluation account.

    The journal will as  given below:
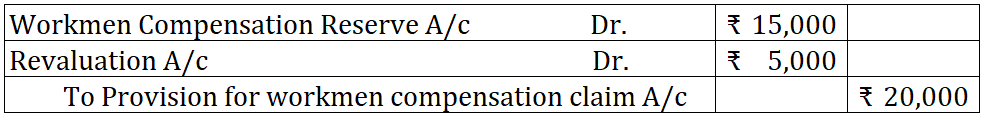
    Since the revaluation account is debited, it is a loss and this loss will be written from old or existing partners’ capital in the old profit sharing ratio. The journal entry is given below:

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Anushka Lalwani
Anushka Lalwani
In: 1. Financial Accounting > Subsidiary Books

Simple petty cash book is like a?

1) Cash Book 2) Statement 3) Journal 4) None of these

  • 1 Answer
  • 0 Followers
Answer
  1. ShreyaSharma none
    Added an answer on August 17, 2022 at 5:22 pm
    This answer was edited.

    1) A simple petty cash book is like a cash book.   Definition The term 'petty' means small. A simple petty cash book is identical to a cash book, maintained to record the small expenses of a business like stationery, postage, stamps, carriage, etc. The cash received by a petty cashier is recordRead more

    1) A simple petty cash book is like a cash book.


    Definition

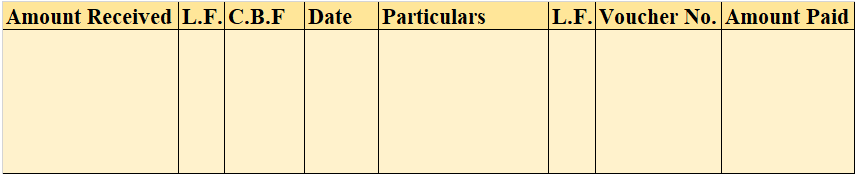
    The term ‘petty’ means small. A simple petty cash book is identical to a cash book, maintained to record the small expenses of a business like stationery, postage, stamps, carriage, etc. The cash received by a petty cashier is recorded on the debit/ receipt side whereas, the cash he pays is recorded on the credit/ payment side. The difference between the sum of the debit and credit items represents the balance of the petty cash in hand.

    Format

    Explanation

    Cash Book – A simple petty cash book is recorded and maintained just like the cash book. Just like a cash book records all the major transactions of the business, a petty cash book only focuses on the expenses which are of little value. Just like the cash book is maintained by the accountant of the business, the petty cash book is maintained by the petty cashier.

    Therefore, a petty cash book is like a sub-part of a cash book itself.

    Statement – A statement in accounting terms refer to a report. They are prepared to show some accounting data and different types of statements show different perspectives of the company’s financial health and performance. For e.g Balance sheet, trial balance, cash flow statements, etc.

    Thus, a petty cash book is not a part of statements in accounting.

    Journal – A petty cash book is not a part of a journal as a journal entry records business transactions in the accounting system for an organization and is also called the building block of the double-entry accounting method. While a petty cash book is maintained to record the small expenses of a business that are of little value.

    Therefore, 1) Cash book is the correct option.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Partnerships

What do you mean by partnership deed?

  • 1 Answer
  • 0 Followers
Answer
  1. Vishnu_K Nil
    Added an answer on November 23, 2022 at 2:26 pm
    This answer was edited.

    Meaning of Partnership Deed A Partnership Deed is a written agreement between partners who are willing to form a Partnership Firm. It is also called as a Partnership Agreement. Contents of a Partnership Deed A Partnership Deed shall mainly include the following contents: Name of the Partnership firmRead more

    Meaning of Partnership Deed

    A Partnership Deed is a written agreement between partners who are willing to form a Partnership Firm. It is also called as a Partnership Agreement.

    Contents of a Partnership Deed

    A Partnership Deed shall mainly include the following contents:

    1. Name of the Partnership firm
    2. Address of the Partnership firm
    3. Details of all the Partners
    4. Date of commencement of the Business
    5. The amount of capital contributed by each of the partners forming the Partnership firm
    6. The Profit sharing ratio (The Business profit shared among the partners on a ratio basis)
    7. The rate or amount of Interest on Capital & the rate or amount of Interest on drawings to each partner respectively.
    8. The salary payable to each of the partners of the firm.
    9. The rights, duties, and power of each partner of the firm.
    10. The duration of the existence of the firm

    Importance of Partnership Deed

    1. Proper regulation of duties, liabilities, and rights of the partners are made in the partnership deed and hence there cannot be any issue during the course of the business.
    2. There can be no disputes between the partners upon Profit sharing, salary, commission, interest on capital, and interest on drawings.
    3. A partnership Deed acts as Legal proof for the conduct of the business and is used for many other registrations such as GST registration, and other related purposes.


    Format of a Partnership Deed

    The Partnership Deed shall originally be executed on an Indian Non-Judicial stamp paper.

    The format of the Partnership deed is given below with an assumption that 4 partners are forming the Partnership.

                                                                    PARTNERSHIP DEED

    This deed of partnership is made on [Date, Month, Year] between:

    1. [First Partner’s Name], [Son/Daughter] of [Mr. Father’s Name], residing at [Address Line 1, Address Line 2, City, State, Pin Code] hereinafter referred to as FIRST PARTNER.

    2. [Second Partner’s Name], [Son/Daughter] of [Mr. Father’s Name], residing at [Address Line 1, Address Line 2, City, State, Pin Code] hereinafter referred to as SECOND PARTNER.

    3. [Third Partner’s Name], [Son/Daughter] of [Mr. Father’s Name], residing at [Address Line 1, Address Line 2, City, State, Pin Code] hereinafter referred to as THIRD PARTNER.

    4. [Fourth Partner’s Name], [Son/Daughter] of [Mr. Father’s Name], residing at [Address Line 1, Address Line 2, City, State, Pin Code] hereinafter referred to as FOURTH PARTNER.


    Whereas, the parties hereto have agreed to commence business in partnership and it is expedient to have a written instrument of partnership. Now, this partnership deed witnesses as follows:

    1. BUSINESS ACTIVITY
    The parties hereto have mutually agreed to carry on the business of [Description of Business Activity Proposed].

    2. PLACE OF BUSINESS
    The principal place of the partnership business will be situated at [Address Line 1, Address Line 2, City, State, Pin Code]

    3. DURATION OF PARTNERSHIP
    The duration of the partnership will be at will.

    4. CAPITAL OF THE FIRM
    Initially, the capital of the firm shall be Rs. [Total Partners Contribution].

    5. PROFIT SHARING RATIO
    The profit or loss of the firm shall be shared equally among all the partners and transferred to the partner’s current account.

    6. MANAGEMENT
    The [First Partner] of the firm shall be Managing Partner and he will look after all the day-to-day transactions of the firm and any legal activities in the name of the firm and the remaining partners shall cooperate to do so.

    7. OPERATION OF BANK ACCOUNTS
    The firm shall open a current account in the name of [Partnership Firm Name] at any bank and such account shall be operated by [First Partner] and [Second Partner] jointly as declared from time to time to the Banks.

    8. BORROWING
    The written consent of all Partners will be required for the partnership to avail credit facilities from any financial institution.

    9. ACCOUNTS
    The firms shall regularly maintain in the ordinary course of business, true and correct accounts of all its transactions and also of all its assets and liabilities, the property books of account, which shall ordinarily be kept at the firm’s place of business. The accounting year shall be the financial year from 1st April onwards and the balance sheet shall be properly audited and the same shall be signed by all the Partners. Every Partner shall have access to the books and the right to verify their correctness.

    10. RETIREMENT
    If any partner shall at any time during the subsistence of the partnership, be desirous of retiring from the firm, it shall be competent from his to do so, provided he shall give at least one calendar month’s notice of his intention of doing so. The remaining partner shall pay the retiring partner or his legal representatives of the deceased partner, the purchase money of his share in the assets of the firm.

    11. DEATH OF PARTNER
    In the event of the death of any partners, one of the legal representatives of the deceased partner shall become the partner of the firm and in the event, the legal representative shows their denial to point the firm, they shall be paid part of the purchase amount calculated as on the date of the death of the partner.

    12. ARBITRATION
    Whenever there by any difference of opinion or any dispute between the partners shall refer the same to the arbitration of one person. The decision of the arbitration so nominated shall be final and binding on all partners, such arbitration proceedings shall be governed by Indian Arbitration Act, which is in force.

    In witness whereof, this deed of partnership is signed sealed, and delivered this [Day, Month, Year] at [City, State]:

    FIRST PARTNER                                            SECOND PARTNER

    [Address Line 1]                                                        [Address Line 1]
    [Address Line 2]                                                        [Address Line 2]
    [City, State, Pin Code]                                              [City, State, Pin Code]

    THIRD PARTNER                                            FOURTH PARTNER

    [Address Line 1]                                                         [Address Line 1]
    [Address Line 2]                                                        [Address Line 2]
    [City, State, Pin Code]                                              [City, State, Pin Code]

    WITNESS ONE                                                  WITNESS TWO

    [Address Line 1]                                                         [Address Line 1]
    [Address Line 2]                                                         [Address Line 2]
    [City, State, Pin Code]                                               [City, State, Pin Code]

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Simerpreet
SimerpreetHelpful
In: 1. Financial Accounting > Partnerships

What comes in debit side of Realisation account?

  • 1 Answer
  • 0 Followers
Answer
  1. Karishma
    Added an answer on September 29, 2023 at 1:29 pm

    Realisation account  A realisation account is a nominal account prepared at the time of dissolution of a business.  All the assets and liabilities except cash and bank balance are transferred to the realisation account. A realisation account is prepared to calculate the profit or loss on the dissoluRead more

    Realisation account 

    A realisation account is a nominal account prepared at the time of dissolution of a business.  All the assets and liabilities except cash and bank balance are transferred to the realisation account. A realisation account is prepared to calculate the profit or loss on the dissolution or closing of the firm.

    All the assets are transferred to the debit of the realisation account and all the liabilities are transferred to the credit of the realisation account. When assets are sold, Cash A/c is debited and Reliastion A/c is credited and when liabilities are paid off, Cash A/c is credited and Realisation A/c is credited.

    If the credit side exceeds the debit side of the realisation account, it results in profit. In contrast, if the debit side exceeds the credit side of the realisation account, it results in a loss. in case of profit, the Capital account is credited and in case of loss, the Capital account is debited.

    The debit side of the realisation account

    All the assets including Land and building, Plant and machinery, furniture, stock, debtor and investment are transferred to the debit of the realisation account and payment of outside liabilities is also recorded on the debit side of the realisation account. Payment made for dissolution expenses is also recorded on the debit side of the realisation account.

    • Assets: All the assets including Land and building, Plant and machinery, Furniture, Stock,  sundry debtors, and investments are transferred to the debit side of the realisation account. The debit balance of profit and loss balance is not transferred.
      • Accounting entry for this is as follows:

    Realisation A/c Dr…..

    To Assets A/c …..

    (All the assets transferred to the realisation account)

    • Cash and bank A/c: Payment for the liabilities including sundry creditors, outstanding expenses, bills payable, loans and advances, bank overdrafts and cash credit is transferred to the debit side of the realisation account.
      • Accounting entry for this is as follows:

    Realisation A/c Dr…..

    To Cash A/c …..

    (Payment made for liabilities)

    • Profit on realisation: If the credit side of the realisation account exceeds the debit side, it results in a profit then the capital account is credited.
      • Accounting entry for this is as follows:

    Realisation A/c Dr…..

    To Capital A/c …..

    (Being profit transferred to the capital account)

    Credit side of realisation account:

    All the liabilities and provisions are transferred to the credit side of the realisation account. Capital account of partners, profit and loss balance and loans from partners are not transferred. Sale proceeds of all the assets including Land and building, Plant and machinery, furniture, stock, debtor and investment are transferred to the credit side of the Realisation account.

    Format for realisation Account is as under:

    Realisation A/c
    Particulars Amount Particulars Amount
    To Land & Building By Provision for Doubtful Debts A/c
    To Plant & Machinery By Sundry Creditors A/c
    To Furniture By Bills Payable A/c
    To Debtors By Outstanding Expenses A/c
    To Goodwill A/c By Bank Loan, Overdraft, Cash Credit A/c
    To Investment A/c By Bank/ Cash A/c (Assets realized):
    To Bank/ Cash A/c (Liabilities Paid): Land and Building
    Sundry Creditors Plant and Machinery
    Bill Payable Furniture
    Outstanding Expenses Stock
    Bank Loan, Debtors
    Overdraft, Bad Debts recovered
    Cash Credit Investment
    To Bank/ Cash A/c By  Capital A/cs
    (Realisation Expenses) (assets taken over)
    To Capital A/c By Capital A/cs
    (Realisation Expenses) (Loss on Realisation)
    To Capital A/cs
    (Profit on Realisation)
    Total Total
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Astha
AsthaLeader
In: 1. Financial Accounting > Financial Statements

Why is miscellaneous expenditure shown in balance sheet?

Balance SheetMiscellaneous Expenditure
  • 1 Answer
  • 0 Followers
Answer
  1. Simerpreet Helpful CMA Inter qualified
    Added an answer on June 25, 2021 at 2:52 pm
    This answer was edited.

    Miscellaneous expenditure in the balance sheet The expenses that are written off in the current financial year are shown on the debit side of the profit and loss account. However, those that are not written off during the current financial year are shown in the balance sheet on the Assets Side as MiRead more

    Miscellaneous expenditure in the balance sheet

    The expenses that are written off in the current financial year are shown on the debit side of the profit and loss account. However, those that are not written off during the current financial year are shown in the balance sheet on the Assets Side as Miscellaneous expenditure.

    Miscellaneous expenditure are those expenses that are not categorized as Operating expenses i.e. these are not classified as manufacturing, selling, and administrative expenses.

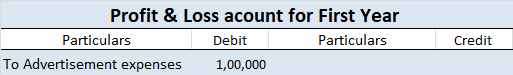
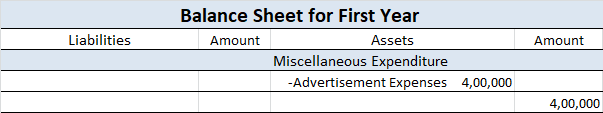
    For example, BlackRock has spent 5,00,000 which will be written of in 5 consecutive years as an Advertisement expense. During the current financial year, only 1,00,000 will be written off and the rest will be carried to the next year and year thereafter.

    Treatment in the first year:

    • 1,00,000 which is written off during the current financial year will be shown on the debit side of the Profit and Loss account.
    • 4,00,000 which is carried forward will be shown on the assets side of the balance sheet as miscellaneous expenditure because all assets and expenses have a debit balance.

    Treatment in the second year:

    • 1,00,000 which is written off during the current financial year will be shown on the debit side of the Profit and Loss account.
    • 4,00,000 which is carried forward will be shown in the assets side of the balance sheet as a miscellaneous expenditure.

    The same will be done in the third, fourth, and fifth years.

    Conclusion

    Deferred revenue expenditure is also a long-term expenditure the benefit of which cannot be derived within the same year. So the amount that is written off during the current year is shown on the debit side of the profit and loss account and the amount which is not written off during the current financial year is shown on the assets side under the head Miscellaneous expenditure.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Jasmeet_Sethi
Jasmeet_SethiCurious
In: 1. Financial Accounting > Depreciation & Amortization

Depreciation in spirit is similar to?

Depletion Amortization Depression

  • 1 Answer
  • 0 Followers
Answer
  1. Simerpreet Helpful CMA Inter qualified
    Added an answer on July 20, 2021 at 2:51 pm
    This answer was edited.

    The correct option is 2. Amortization. Depreciation in spirit is similar to Amortization because both depreciation and amortization have the same characteristics except that depreciation is used for tangible assets and amortization for intangible assets. To make it clear, intangible assets are thoseRead more

    The correct option is 2. Amortization.

    Depreciation in spirit is similar to Amortization because both depreciation and amortization have the same characteristics except that depreciation is used for tangible assets and amortization for intangible assets.

    To make it clear, intangible assets are those assets that cannot be touched i.e. they are not physically present. For example, goodwill, patent, trademark, etc. Hence, these assets are amortized over their useful life and not depreciated.

    Example for Amortizing intangible assets: A manufacturing company buys a patent for Rs 80,000 for 8 years. Assuming that the residual value of the patent after 8 years to be zero.

    The depreciation to be written off will be

    Yearly Depreciation = Cost of the patent – Residual value / Expected life of the asset.

    = 80,000 – 0 / 8

    = Rs 10,000 every year.

    Whereas, tangible assets are those assets that can be touched i.e. they are physically present. For example, building, plant & machinery, furniture, etc. Hence, these assets are depreciated over their useful life and not amortized.

    Example of Depreciating tangible asset:  A manufacturing company bought machinery for Rs 8,10,000 and its estimated life is 8 years, scrap value being Rs 10,000.

    The depreciation to be written off will be

    Yearly Depreciation = Cost of machinery – Scrap value / Expected life of the asset.

    = 8,10,000 – 10,000 / 8

    = 8,00,000 / 8

    = Rs 1,00,000 every year.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Astha
AsthaLeader
In: 1. Financial Accounting > Journal Entries

What is the journal entry for sale of asset?

  • 1 Answer
  • 0 Followers
Answer
  1. Manvi Pursuing ACCA
    Added an answer on August 5, 2021 at 2:52 pm
    This answer was edited.

    An asset is an item of property owned by a company/business. It may be for a longer or shorter period of time. Assets are classified into two broad heads: Non-Current Assets Current Assets   The asset may be sold for several reasons such as: An asset is fully depreciated. It should be sold becaRead more

    An asset is an item of property owned by a company/business. It may be for a longer or shorter period of time. Assets are classified into two broad heads:

    1. Non-Current Assets
    2. Current Assets


    The asset may be sold for several reasons such as:

    1. An asset is fully depreciated.
    2. It should be sold because it is no longer needed.
    3. It is removed from the books due to unforeseen circumstances.


    The journal entry for profit on the sale of assets will be:

    Cash / Bank A/c Debit
             To Asset A/c Credit
             To Profit on Sale of Asset A/c Credit
    (Being sale of an asset made with a gain)

    According to the golden rules of accounting, in the above entry “Cash/Bank A/c” it is a Real Account and the rule says “Debit what comes in” and so is debited.

    “Asset A/c” is a real account and the rule says “Credit what goes out” and so is credited. Any Gain on sale of an asset goes to the Nominal account and according to the rule “Credit, all incomes and gains” and so is credited.


    The journal entry for loss on sale of the asset will be:

    Cash / Bank A/c Debit
    Loss on Sale of Asset A/c Debit
             To Asset A/c Credit
    (Being sale of an asset made and loss incurred)

    In the above entry, “Loss on Sale of Asset” is debited because according to Nominal account rules “Debit all losses and expenses” and so is debited.

    According to modern rules of accounting, “Debit entry” increases assets and expenses, and decreases liability and revenue, a “Credit entry” increases liability and revenue, and decreases assets and expenses.

    Cash / Bank A/c Debit Increases Asset
    Loss on Sale of Asset A/c Debit Increases Expenses
             To Asset A/c Credit Decreases Asset
             To Profit on Sale of Asset A/c Credit Increases Expenses


    For example, Mr. A sold furniture for $2,500 and incurred a loss on the sale which amounted to $2,500.

    According to modern rules, the journal entry will be:

    Particulars Amt Amt  
    Cash / Bank A/c 2,500 Increase in asset
    Loss on Sale of Asset A/c 2,500 Increase in expenses
             To Asset A/c 5,000 Decrease in asset
    (Being sale of an asset made and loss incurred)
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
AbhishekBatabyal
AbhishekBatabyalHelpful
In: 1. Financial Accounting > Depreciation & Amortization

How much is depreciation on camera?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on October 5, 2021 at 10:29 am
    This answer was edited.

    The Income Tax 1961 does not provide any rate of depreciation specifically for cameras. But we can consider camera within the block of ‘Computer including software’ for which the rate of depreciation is 40% at WDV method. It is a general practice for non-corporates to charge depreciation at rates slRead more

    The Income Tax 1961 does not provide any rate of depreciation specifically for cameras. But we can consider camera within the block of ‘Computer including software’ for which the rate of depreciation is 40% at WDV method.

    It is a general practice for non-corporates to charge depreciation at rates slightly lower than the rate provided by the Income Tax Act, 1961. But one cannot charge depreciation more than it.

    In the case of corporate, the rates for charging depreciation are provided by the Companies Act 2013, which is

    • 20.58% WDV and 7.31% SLM for cameras to be used for the production of cinematography and motion pictures.
    • 25.89% WDV and 9.50% SLM for cameras which is part of electrical installations and equipment (CCTV cameras).

    Let’s take an example:

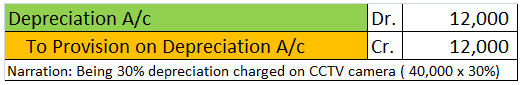
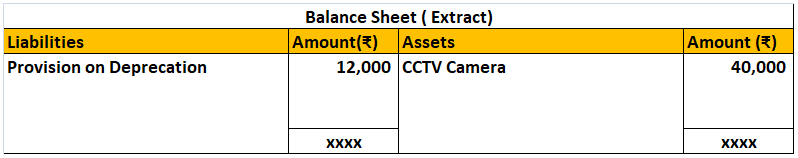
    Mr X is a jewellery shop owner and has installed CCTV cameras on 1st April 2021, costing ₹ 40,000 at various points in his shop to ensure safety and security. Keeping in mind the Income-tax rates, his accountant decided to charge depreciation @ 30% p.a. on the CCTV cameras.

    Following is the journal entry:

    The balance sheet will look like this:

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Spriha Sparsh
Spriha Sparsh
In: 1. Financial Accounting > Miscellaneous

Can working capital be negative?

  • 1 Answer
  • 0 Followers
Answer
  1. Radhika
    Added an answer on November 18, 2021 at 6:56 am
    This answer was edited.

    Working Capital is the capital used in the daily operations of the business. It is calculated as the difference between current assets and current liabilities. Gross working capital means current assets and net working capital means the difference between current assets and current liabilities. WorkRead more

    Working Capital is the capital used in the daily operations of the business. It is calculated as the difference between current assets and current liabilities. Gross working capital means current assets and net working capital means the difference between current assets and current liabilities.

    Working Capital indicates the short-term liquidity of its business. It means the ability of a company to meet its daily requirements through short-term financing.

    Working Capital can be;

    • Positive
    • Zero, or
    • Negative

    Positive or negative working capital follows a simple rule of math. If current assets are more than current liabilities, working capital is positive and if current assets are less than current liabilities, working capital is negative. When current assets are equal to current liabilities, working capital is zero.

    Negative working capital for a short period means that the company has made a big payment to its vendors, or a significant increase in the creditor’s account because of credit purchases.

    However, if working capital is negative for a longer period it indicates that the company is struggling with its operating requirements or that it has to finance its daily operations through long-term borrowings.

    The current ratio for a company is calculated as: 

    Current Assets divided by Current Liabilities.

    Working Capital and Current Ratio are interrelated. If the Current Ratio is more than 1, it means current assets exceed current liabilities and Working Capital is positive. However, if the Current Ratio is less than 1, it means current liabilities exceed current assets and Working Capital is negative.

    For example-

    If Current Assets are Rs 50,000 and Current Liabilities are Rs 70,000 then

    Working Capital= Current Assets – Current Liabilities

    WC           =        Rs 70,000   –     Rs 50,000

    WC           =                   Rs. 20,000

    Current Ratio = Current Assets / Current Liabilities

    CR        =         Rs.50,000/ Rs. 70,000

    CR        =                           0.71< 1


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.