Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Most Visited
  • Most Voted
  • Followed Questions
  • Most Answered
  • No Answers

AccountingQA Latest Questions

A_Team
A_Team
In: 1. Financial Accounting > Partnerships

What are the types of partners in partnership act 1932?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on September 28, 2021 at 4:43 pm

    The partnership act 1932 does not mention the types of partners specifically. It does have mentions of ‘partner who is minor’ in section 30 and ‘partner by holding out in section 28. But we do come across many types of partners in partnership firms. Following is the list of the types of partners weRead more

    The partnership act 1932 does not mention the types of partners specifically. It does have mentions of ‘partner who is minor’ in section 30 and ‘partner by holding out in section 28.

    But we do come across many types of partners in partnership firms. Following is the list of the types of partners we generally see:-

    1. Active partner: – It is the partner who provides the capital and is also actively involved in the management and daily activities of the firm. Such a type of partner is of utmost importance to the firm. Apart from a share in profit and loss, he is also eligible to draw remuneration from the firm.


    1. Sleeping/ Dormant partner: – This type of partner does not participate in the daily workings of the firm nor actively participates in the management of the firm. Such a type of partner has a large sum of capital invested in the firm and shares the profits as well as losses of the firm.


    1. Partner by holding out:- If any partner, who by his words or by his conduct, represents himself as a partner of a firm, then he is called a partner by holding out. Such a partner is actually not a partner of the firm and doesn’t receive any share of profit as he has contributed no capital.

    As per section 28, such a partner is liable to any person who has given credit to the firm on             the belief that he is a partner of the firm.


    1. Minor partner: – If any person who is less than 18 years of age is admitted into the firm, such partner is known as a minor partner. Such a partner is entitled to the profits of the firm based on his capital but is immune from losses suffered by the firm.


    1. Secret partner: – It is a partner of a firm whose membership is kept hidden from the outsiders such as creditors and other third parties. But he is equally liable as other partners for the outside liabilities.


    1. Outgoing partner: – A partner who voluntarily leaves the partnership without dissolving the firm is called an outgoing partner or retiring partner. Such a partner is liable to all liabilities incurred before his retirement. But he can be held liable to outside liabilities if he fails to give public notice of his retirement.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Karan
Karan
In: 1. Financial Accounting > Partnerships

What is the difference between dissolution of partnership and dissolution of firm?

Difference BetweenDissolution of FirmDissolution of Partnership
  • 1 Answer
  • 0 Followers
Answer
  1. PriyanshiGupta Graduated, B.Com
    Added an answer on November 12, 2021 at 1:35 pm
    This answer was edited.

    Dissolution of partnership means partnership coming to an end while the firm still stands. Various reasons for the dissolution of partnership could be: Admission of a partner Death of a partner Retirement of a partner Dissolution of firm In the event of the above cases, the existing partnership is dRead more

    Dissolution of partnership means partnership coming to an end while the firm still stands. Various reasons for the dissolution of partnership could be:

    • Admission of a partner
    • Death of a partner
    • Retirement of a partner
    • Dissolution of firm

    In the event of the above cases, the existing partnership is dissolved and a new partnership is created with the new partners without affecting the firm.

    A new partnership deed is created, in case there is a partnership deed agreed among partners and new profit-sharing ratios among the partners are decided, while the assets and liabilities of the firm remain the same.

    Dissolution of a firm means the firm no longer exists. Various reasons for the dissolution of a partnership firm could be:

    • Mutual decision of partners
    • By the court of law

    A partnership firm is dissolved by a court of law when there has been a non-compliance of law, the firm is engaged in illegal practices, or that the court’s opinion is that it is in the public interest for the firm to be dissolved.

    The partnership is also dissolved with the dissolution of the firm but the converse need not be true.

    When a firm is dissolved, there is a sequence that is followed to pay creditors and partners.

    • First, outside creditors like banks, third party creditors are paid firstly with the cash available with the firm and then by selling the assets.
    • Second, partners who have lent money in the form of a loan to the firm are paid.
    • Lastly, if there is any surplus, partners are paid with the amount of their capital. In case of loss, partners are required to pay from their personal assets.

    Dissolution of the firm can be done by the partners themselves and they could also appoint a third person to do so on the payment of fees, charges, the proportion of surplus, or any contract that has been agreed to.

    To summarize, we can a draw a difference table as follows:

    Dissolution of Partnership Dissolution of Partnership Firm
    The partnership ends but the firm still stands. A partnership firm no longer exists.
    A new partnership deed is created by the mutual agreement of partners. A new partnership firm is created if the partners decide.
    Reasons:

    ·        Admission

    ·        Retirement

    ·        Death

    Reasons:

    ·        By court

    ·        Mutual decision of partners

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Radha
Radha
In: 1. Financial Accounting > Accounting Terms & Basics

What is a capital asset?

  • 1 Answer
  • 0 Followers
Answer
  1. AbhishekBatabyal Helpful Pursuing CA, BCOM (HONS)
    Added an answer on December 7, 2021 at 7:29 pm

    Meaning Capital assets mean the assets which are used in the business operations to generate revenue. The benefit from these assets is expected to flow to the enterprise beyond the time span of one year. Capital assets are commonly called fixed assets. Examples of capital assets are plant, machineryRead more

    Meaning

    Capital assets mean the assets which are used in the business operations to generate revenue. The benefit from these assets is expected to flow to the enterprise beyond the time span of one year. Capital assets are commonly called fixed assets.

    Examples of capital assets are plant, machinery, land, building, vehicles etc.

    To expense the capital assets for the economic benefits they provide, they are depreciated over their useful life on some equitable basis.

    When capital assets are sold, the gain on sale is credited to the capital reserve account. On loss, it is simply debited to the profit and loss account. Capital assets are shown under the heading ‘Plant, Property and Equipment’ under the asset head of the balance sheet.

    Assets that do not qualify as capital assets

    The assets which provide economic benefits for less than a year do not qualify as capital assets. Such as inventories, accounts receivables etc. are not capital assets.

    Also, those assets which are not intended to be held for more than 1 year are not capital assets even if such assets are capable of providing economic benefits for more than 1 year. Such assets will be considered current assets.

    For example, if a plot of land is purchased by a business but the intention is to sell it after 2 months then such land will not be considered a capital asset.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
AbhishekBatabyal
AbhishekBatabyalHelpful
In: 1. Financial Accounting > Accounting Terms & Basics

What is a valuation account?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on January 11, 2022 at 7:07 pm
    This answer was edited.

    Meaning A valuation account is a balance sheet account that is paired with another balance sheet account to report the carrying amount of the paired account at a reduced value. The purpose of a valuation account is to reduce the balance of the concerned asset or liability without affecting the mainRead more

    Meaning

    A valuation account is a balance sheet account that is paired with another balance sheet account to report the carrying amount of the paired account at a reduced value.

    The purpose of a valuation account is to reduce the balance of the concerned asset or liability without affecting the main ledger account.  This is a conservative approach to use valuation accounts to present the value of the concerned asset or liability at a reduced value.

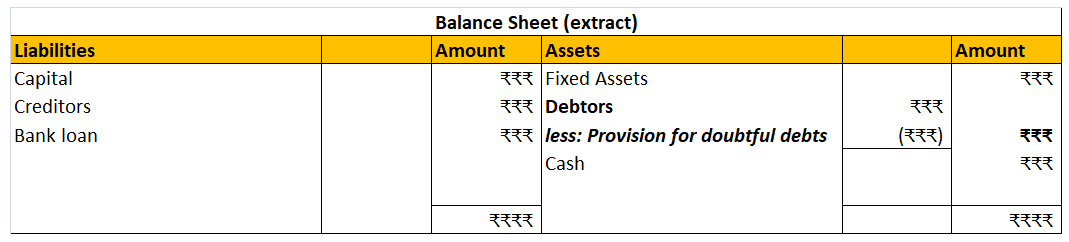
    The most common example of a valuation account is the ‘Provision for doubtful debts account’. It appears in the balance sheet as a reduction from the debtors’ accounts. Also when the amount is transferred to this provision, it appears in the statement of profit and loss account. But it doesn’t appear in the debtors’ account ledger.

    Treatment

    A valuation account appears only in the balance sheet. Sometimes, it also appears in the profit and loss account when any amount is transferred to it.

    Valuation accounts are only used in accrual accounting. They cannot be used in cash-based accounting as there is no flow of cash related to valuation accounts.

    They have a balance opposite of their paired accounts i.e. if their paired account is an asset then they will have a credit balance and if it is a liability then they will have a debit balance.

    Other Examples of valuation accounts are as follows:

    1. Provision for doubtful debts (offsets the account receivables or debtors’ account)
    2. Accumulated depreciation (report the assets net of depreciation)
    3. Discount on bonds payable (reduces the reporting balance of bond payable account)
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Miscellaneous

What are non debt capital receipts?

  • 1 Answer
  • 0 Followers
Answer
  1. GautamSaxena Curious .
    Added an answer on August 6, 2022 at 6:41 pm
    This answer was edited.

    Non-debt capital receipts As we're aware, there are two main sources of the government’s income — revenue receipts and capital receipts. Revenue receipts are all those receipts that neither create any liability nor cause any reduction in assets for the government, whereas, capital receipts are thoseRead more

    Non-debt capital receipts

    As we’re aware, there are two main sources of the government’s income — revenue receipts and capital receipts. Revenue receipts are all those receipts that neither create any liability nor cause any reduction in assets for the government, whereas, capital receipts are those money receipts of the government that either create a liability for a government or cause a reduction in assets.

    Revenue receipts comprise both tax and non-tax revenues while capital receipts consist of capital receipts and non-debt capital receipts. Non-debt capital receipt is a part of capital receipt.

    Definition

    Non-debt capital receipts, also known as NDCR, are the taxes and duties levied by the government forming the biggest source of its income. Those receipts of the government lead to a decrease in assets, and not an increase in liabilities. It accounts for just 3% of the central government’s total receipts.

    The union government usually lists non-debt capital receipts in two categories:

    • Recovery of loans – Recovery of loans means the amount recovered when a loan defaults.
    • Other receipts – Other receipts basically mean disinvestment proceeds from the sale of the government’s share in public-sector companies.
    • Money accrued to the union government from the listing of central government companies and the issue of bonus shares.


    For Example – Disinvestment and recovery of loans are non-debt creating capital receipts.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Accounting Terms & Basics

What is a non-current asset?

  • 1 Answer
  • 0 Followers
Answer
  1. Akash Kumar AK
    Added an answer on November 26, 2022 at 8:06 am
    This answer was edited.

    Generally, Assets are classified into two types. Non-Current Assets Current Assets   Non-Current Asset Noncurrent assets are also known as Fixed assets. These assets are an organization's long-term investments that are not easily converted to cash or are not expected to become cash within an acRead more

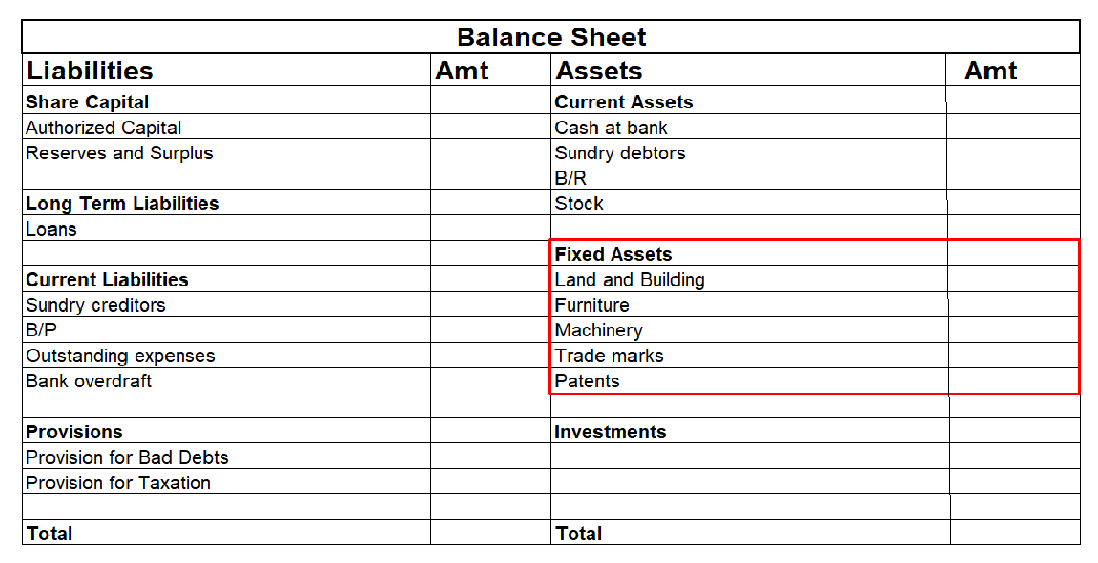
    Generally, Assets are classified into two types.

    1. Non-Current Assets
    2. Current Assets


    Non-Current Asset

    Noncurrent assets are also known as Fixed assets. These assets are an organization’s long-term investments that are not easily converted to cash or are not expected to become cash within an accounting year.

    In general terms, In accounting, fixed assets are assets that cannot be converted into cash immediately. They are primarily tangible assets used in production having a useful life of more than one accounting period. Unlike current assets or liquid assets, fixed assets are for the purpose of deriving long-term benefits.

    Unlike other assets, fixed assets are written off differently as they provide long-term income. They are also called “long-lived assets” or “Property Plant & Equipment”.


    Examples of Fixed Assets

    • Land
    • Land improvement (e.g. irrigation)
    • Building
    • Building (work in progress)
    • Machinery
    • Vehicles
    • Furniture
    • Computer hardware
    • Computer software
    • Office equipment
    • Leasehold improvements (e.g. air conditioning)
    • Intangible assets like trademarks, patents, goodwill, etc. (non-current assets)


    Valuation of Fixed asset

    fixed assets are recorded at their net book value, which is the difference between the “historical cost of the asset” and “accumulated depreciation”.

    “Net book value = Historical cost of the asset – Accumulated depreciation”


    Example:

    Hasley Co. purchases Furniture for their company at a price of 1,00,000. The Furniture has a constant depreciation of 10,000 per year. So, after 5 years, the net book value of the computer will be recorded as

    1,00,000 – (5 x 10,000) = 50,000.

    Therefore, the furniture value should be shown as 50,000 on the balance sheet.


    Presentation in the Balance Sheet

    Both current assets and non-current assets are shown on the asset side(Right side) of the balance sheet.


    Difference between Current Asset and Non-Current Asset

    Current assets are the resources held for a short period of time and are mainly used for trading purposes whereas Fixed assets are assets that last for a long time and are acquired for continuous use by an entity.

    The purpose to spend on fixed assets is to generate income over the long term and the purpose of the current assets is to spend on fixed assets to generate income over the long term.

    At the time of the sale of fixed assets, there is a capital gain or capital loss but at the time of the sale of current assets, there is an operating gain or operating loss.

    The main difference between the fixed asset and current asset is, although both are shown in the balance sheet fixed assets are depreciated every year and it is valued by (the cost of the asset – depreciation) and current asset is valued as per their current market value or cost value, whichever is lower.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
SidharthBadlani
SidharthBadlani
In: 1. Financial Accounting > Miscellaneous

Can someone give examples of net profit and gross profit?

  • 1 Answer
  • 6 Followers
Answer
  1. Ishika Pandey Curious ca aspirant
    Added an answer on February 5, 2023 at 12:58 pm
    This answer was edited.

    Definition Gross profit is the excess of the proceeds of goods and services rendered during a period over their cost, before taking into account administration, selling, distribution, and financial expenses. Gross profit and net profit are gross profit estimates of the profitability of a company. WhRead more

    Definition

    Gross profit is the excess of the proceeds of goods and services rendered during a period over their cost, before taking into account administration, selling, distribution, and financial expenses.

    Gross profit and net profit are gross profit estimates of the profitability of a company.

    When the result of this computation is negative it is referred to as gross loss

    Formula :

    Total Revenues – Cost Of Goods Sold

    Net profit is defined as the excess of revenues over expenses during a particular period.
    Net profit is to show the performance of the company.

    When the result of this computation is negative it is called a net loss.

    Net profit may be shown before or after tax.

    Formula :

    Total Revenues – Expenses
    Or
    Total Revenues – Total Cost ( Implicit And Explicit Cost )

    Examples

    Now let me explain to you by taking an example which is as follows :

    In a business organization there were the following data given as purchases made Rs 73000, inventory, in the beginning, was Rs 10000, direct expenses made were Rs 7000, closing inventory which was Rs 5000, revenue from operation during the period was Rs 100000.
    Then,

    COST OF GOODS SOLD = Purchases + Opening Inventory + Direct Expenses – Closing Inventory.

    = Rs ( 73000 + 10000+ 7000- 5000)
    = Rs 85000

    GROSS PROFIT = REVENUE – COST OF GOODS SOLD

    = Rs ( 100000 – 85000 )
    = Rs 15000

    Now from the above question keeping the gross profit same if the indirect expenses of the organization are Rs 2000 and the other income is Rs 1000.
    Then,

    NET PROFIT = GROSS PROFIT – INDIRECT EXPENSES + OTHER INCOMES

    = Rs ( 15000 – 2000 + 1000)
    = Rs 14000

    Treatment

    Treatment of gross profit and net profit is given as follows :

    Gross profit

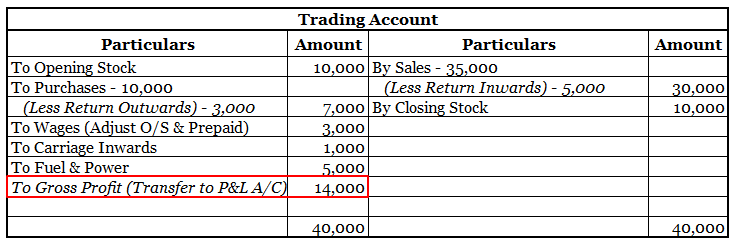
    • Gross profit appears on the credit side of the trading account.
    • Gross profit is located in the upper portion beneath revenue and cost of goods sold.

    Net profit

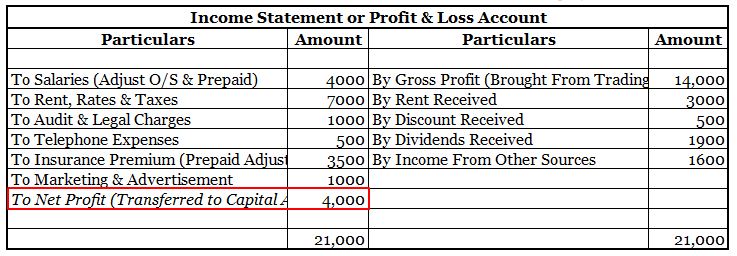
    • Net profit appears on the credit side of the profit and loss account.
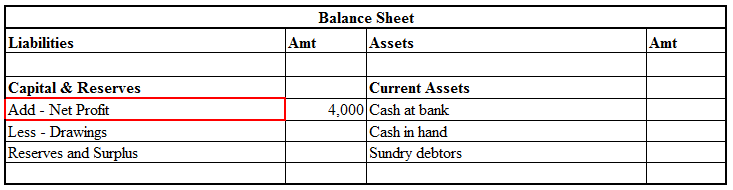
    • It is treated directly in the balance sheet by adding or subtracting from the capital.

    Here is an extract of the trading and profit/loss account and balance sheet showing GROSS PROFIT & NET PROFIT :

    See less
    • 1
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Mehak
Mehak
In: 1. Financial Accounting > Accounting Terms & Basics

What are biological assets? What is their accounting treatment?

  • 1 Answer
  • 0 Followers
Answer
  1. Aditi
    Added an answer on January 12, 2025 at 7:40 am

    Biological Assets comes under International Accounting Standard IAS 41 Agriculture. IAS 41 Agriculture is the first standard that specifically covers the primary sector. The scope of IAS 41 is accounting for agricultural activity. Agricultural Activity- It is the management of biological transformatRead more

    Biological Assets comes under International Accounting Standard IAS 41 Agriculture.

    IAS 41 Agriculture is the first standard that specifically covers the primary sector. The scope of IAS 41 is accounting for agricultural activity.

    • Agricultural Activity- It is the management of biological transformation by an entity and measuring the change in the quality and quantity of biological assets.
    • Biological Transformation- It comprises the process of growth, degeneration, production and procreation that cause qualitative or quantitative changes in a biological asset
    • Biological Asset – They are living plants or animals owned by an entity
    • Agricultural Produce- It is the harvested / detached product of the entity’s biological asset.

    IAS 41 does not apply to

    • Agricultural land
    • Intangible assets related to agricultural activity
    • Products that are the result of processing after the point of harvest, for example, yarn, carpet, rubber, wine, etc
    • The land on which the biological assets grow, regenerate, degenerate.


    Biological Assets

    Definition

    Biological assets are living plants or animals that go through biological transformation, owned by an entity to prepare agricultural produce for the purpose of agricultural activities only.

    Living plants include plants that are consumable within 1 year and are harvested. It also includes plants that are used for lumbering and wood-cutting activities.

    Examples

    Examples of biological assets are:

    Sheep, pigs, poultry, beef cattle, fish, dairy cows, plants for harvest etc

    Importance

    • Farming: They are key to agriculture and food production.
    • Income: They generate substantial income for businesses in industries such as vineyards, livestock, silviculture, etc.
    • Sustainability: Properly managing them helps the environment.


    Accounting & Presentation

    Recognition

    Under IAS 41 biological assets are recognised when

    • The business must have ownership over them from a past event.
    • The future economic benefits are expected to flow to the business from their ownership.
    • The cost or fair value of the asset can be measured reliably.

    Agricultural produce is recognised

    • It is recognised at the point of harvest or detachment.

    Agricultural produce is derecognised when

    • They enter the trading.
    • Enters the production process.

    Measurement

    • Biological assets are measured on initial recognition and at each balance sheet date at their fair value less costs to sell.
    • Costs to sell are incremental costs incurred in selling the asset.
    • Agricultural produce is measured at the point of harvest, at fair value less costs to sell at the point of harvest.
    • Agricultural produce after the point of harvest/ detachment is transferred and treated under the IAS 2 Inventory

    Gains & Losses

    • Gains and losses arising from the initial recognition of biological assets are reported in the statement of profit and loss.
    • The change in fair value less costs to sell of a biological asset between balance sheet dates is reported as gain or loss in the statement of profit and loss.
    • A gain or loss arising on initial recognition of agricultural produce at fair value less selling costs is included in profit or loss for the period in which it arises.

    Treatment

    • The sale of agricultural produce is treated as revenue in the statement of profit and loss.
    • Agricultural produce to be harvested for more than 12 months, livestock to be held for more than 12 months and trees cultivated for lumber are recorded as Biological assets under the Non-current assets head in the balance sheet.
    • Agricultural produce to be harvested within 12 months, livestock to be slaughtered within 12 months and annual crops like wheat, and maize are recorded as Biological assets under the head Current assets in the balance sheet.
    • Inventories produced from agricultural produce are presented as Inventory under the head Current assets in the balance sheet.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Bonnie
BonnieCurious
In: 1. Financial Accounting > Shares & Debentures

Can you explain calls in advance as per the companies act?

Calls in AdvanceCompanies Act
  • 1 Answer
  • 0 Followers
Answer
  1. Naina@123 (B.COM and CMA-Final)
    Added an answer on June 30, 2021 at 8:16 pm
    This answer was edited.

    To begin with, lets us understand what the Companies Act 2013 tells about calls-in-advance, so basically as per section 50 of the companies act 2013 "A company may if so authorized by its articles, accepts from any members the whole or part of amount remaining unpaid on any share held by him, even iRead more

    To begin with, lets us understand what the Companies Act 2013 tells about calls-in-advance, so basically as per section 50 of the companies act 2013 “A company may if so authorized by its articles, accepts from any members the whole or part of amount remaining unpaid on any share held by him, even if no amount has been called up”.

    To be more precise whenever excess money is received by the company than, what has been called up is known as calls-in-advance.

    Accounting Treatment

    Well, it is to be noted that calls-in-advance is never a part of share capital. A company when authorized by its article can accept those advance amounts and directly credit the amount received to the calls-in-advance account.

    As these advance amounts are a liability for the company these are shown under the head current liability of the balance sheet until calls are made and are paid to the shareholders.

    Since this is the liability of the company, it is liable to pay the interest amount on such call money from the date of receipt until the payment is done to the shareholders. The rate of interest is mentioned in the articles of association. If the article is silent regarding the rate on which interest is paid then it is assumed to be @6%.

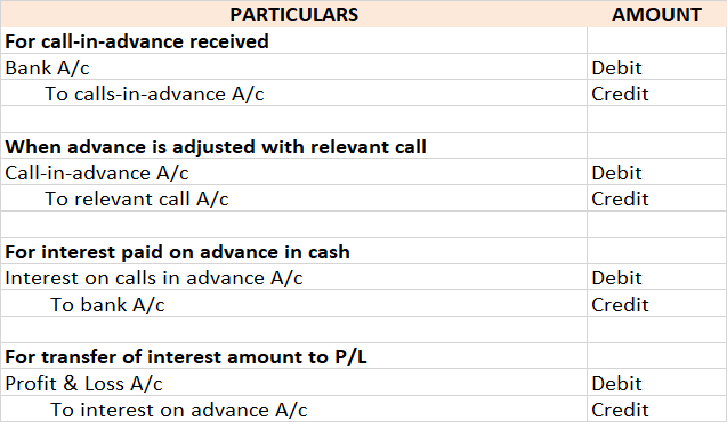
    Accounting Entry

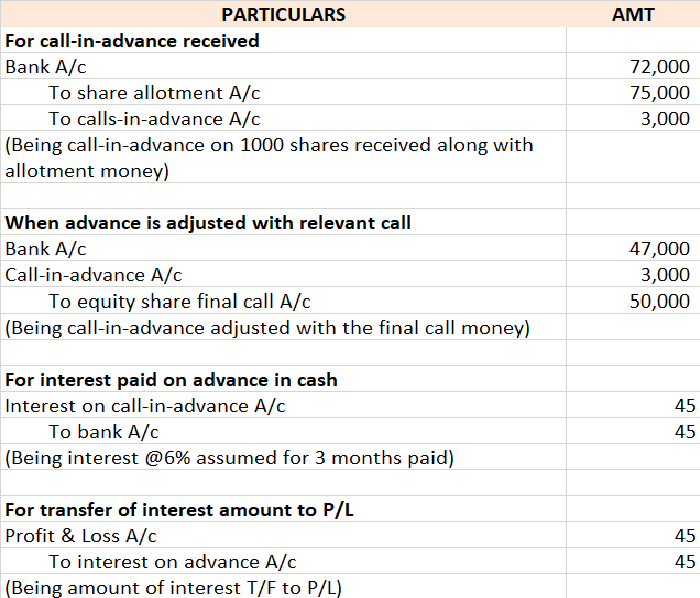
    Bonnie let us understand the entries with help of an example

    ADIDAS LTD issued 25,000 equity shares of Rs 10 each payable as follows:

    ON APPLICATION  Rs 5

    ON ALLOTMENT    Rs 3

    ON FINAL CALL     Rs 2

    Application on 30,000 shares was received. excess money received on the application was refunded immediately. Mr. X who was allotted 1,000 shares paid the call money at the time of allotment and all amounts were duly received assume interest rate @6% for 3 months, so the relevant accounting entry goes as follows:

    Important Points to be noted under calls-in-advance as per the companies act 2013

    • The shareholder is not entitled to any voting rights on money paid until the said money is called for.
    • No dividends are payable on advance money.
    • Board may pay interest on advance not exceeding 12%.
    • The shareholders are entitled to claim the interest amount as mentioned in the article, if there are no profits, then it must be paid out of capital because shareholders become the creditors of the company.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Vijay
VijayCurious
In: 1. Financial Accounting > Depreciation & Amortization

Explain with rates furniture and fixtures depreciation.

  • 1 Answer
  • 0 Followers
Answer
  1. Simerpreet Helpful CMA Inter qualified
    Added an answer on July 23, 2021 at 3:29 pm
    This answer was edited.

    The Furniture and Fixture is depreciated @10% according to the income tax act and as per the companies act, 2013 @9.50% under Straight line method and @25.89% under written down value method. Furniture and fixture form a major part to furnish an office. For Example, the chair, table, bookshelves, etRead more

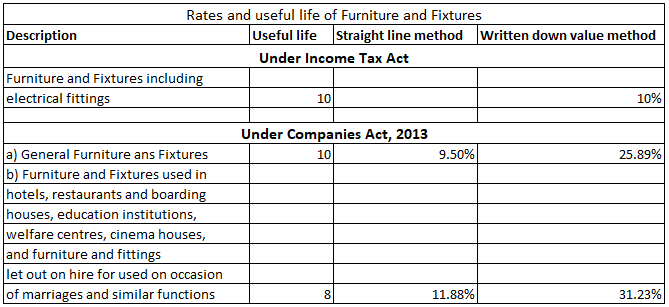
    The Furniture and Fixture is depreciated @10% according to the income tax act and as per the companies act, 2013 @9.50% under Straight line method and @25.89% under written down value method.

    Furniture and fixture form a major part to furnish an office. For Example, the chair, table, bookshelves, etc. all comes under Furniture and Fixture. The useful life of Furniture and Fixtures is estimated as 5-10 years depending upon the kind of furniture.

    Rate of depreciation in reference to days

    • If Furniture is bought and put to use for more than 180 days, then the full rate of depreciation will be charged.
    • If the furniture is bought and put to use for less than 180 days, then half the rate of depreciation will be charged.
    • If the furniture is bought but is not put to use, then no depreciation will be charged.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.