Please briefly explain why you feel this question should be reported.

Please briefly explain why you feel this answer should be reported.

Please briefly explain why you feel this user should be reported.

Sign InSign Up

AccountingQA

AccountingQA Logo AccountingQA Logo

AccountingQA Navigation

  • Home
  • Ask Questions
  • Write Answers
  • Explore
  • FAQs
Search
Ask A Question

Mobile menu

Close
Ask a Question
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion
  • Search Your Accounting Question..

  • Most Visited
  • Most Voted
  • Followed Questions
  • Most Answered
  • No Answers

AccountingQA Latest Questions

Mehak
Mehak
In: 1. Financial Accounting > Accounting Terms & Basics

What are biological assets? What is their accounting treatment?

  • 1 Answer
  • 0 Followers
Answer
  1. Aditi
    Added an answer on January 12, 2025 at 7:40 am

    Biological Assets comes under International Accounting Standard IAS 41 Agriculture. IAS 41 Agriculture is the first standard that specifically covers the primary sector. The scope of IAS 41 is accounting for agricultural activity. Agricultural Activity- It is the management of biological transformatRead more

    Biological Assets comes under International Accounting Standard IAS 41 Agriculture.

    IAS 41 Agriculture is the first standard that specifically covers the primary sector. The scope of IAS 41 is accounting for agricultural activity.

    • Agricultural Activity- It is the management of biological transformation by an entity and measuring the change in the quality and quantity of biological assets.
    • Biological Transformation- It comprises the process of growth, degeneration, production and procreation that cause qualitative or quantitative changes in a biological asset
    • Biological Asset – They are living plants or animals owned by an entity
    • Agricultural Produce- It is the harvested / detached product of the entity’s biological asset.

    IAS 41 does not apply to

    • Agricultural land
    • Intangible assets related to agricultural activity
    • Products that are the result of processing after the point of harvest, for example, yarn, carpet, rubber, wine, etc
    • The land on which the biological assets grow, regenerate, degenerate.


    Biological Assets

    Definition

    Biological assets are living plants or animals that go through biological transformation, owned by an entity to prepare agricultural produce for the purpose of agricultural activities only.

    Living plants include plants that are consumable within 1 year and are harvested. It also includes plants that are used for lumbering and wood-cutting activities.

    Examples

    Examples of biological assets are:

    Sheep, pigs, poultry, beef cattle, fish, dairy cows, plants for harvest etc

    Importance

    • Farming: They are key to agriculture and food production.
    • Income: They generate substantial income for businesses in industries such as vineyards, livestock, silviculture, etc.
    • Sustainability: Properly managing them helps the environment.


    Accounting & Presentation

    Recognition

    Under IAS 41 biological assets are recognised when

    • The business must have ownership over them from a past event.
    • The future economic benefits are expected to flow to the business from their ownership.
    • The cost or fair value of the asset can be measured reliably.

    Agricultural produce is recognised

    • It is recognised at the point of harvest or detachment.

    Agricultural produce is derecognised when

    • They enter the trading.
    • Enters the production process.

    Measurement

    • Biological assets are measured on initial recognition and at each balance sheet date at their fair value less costs to sell.
    • Costs to sell are incremental costs incurred in selling the asset.
    • Agricultural produce is measured at the point of harvest, at fair value less costs to sell at the point of harvest.
    • Agricultural produce after the point of harvest/ detachment is transferred and treated under the IAS 2 Inventory

    Gains & Losses

    • Gains and losses arising from the initial recognition of biological assets are reported in the statement of profit and loss.
    • The change in fair value less costs to sell of a biological asset between balance sheet dates is reported as gain or loss in the statement of profit and loss.
    • A gain or loss arising on initial recognition of agricultural produce at fair value less selling costs is included in profit or loss for the period in which it arises.

    Treatment

    • The sale of agricultural produce is treated as revenue in the statement of profit and loss.
    • Agricultural produce to be harvested for more than 12 months, livestock to be held for more than 12 months and trees cultivated for lumber are recorded as Biological assets under the Non-current assets head in the balance sheet.
    • Agricultural produce to be harvested within 12 months, livestock to be slaughtered within 12 months and annual crops like wheat, and maize are recorded as Biological assets under the head Current assets in the balance sheet.
    • Inventories produced from agricultural produce are presented as Inventory under the head Current assets in the balance sheet.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Bonnie
BonnieCurious
In: 1. Financial Accounting > Shares & Debentures

Can you explain calls in advance as per the companies act?

Calls in AdvanceCompanies Act
  • 1 Answer
  • 0 Followers
Answer
  1. Naina@123 (B.COM and CMA-Final)
    Added an answer on June 30, 2021 at 8:16 pm
    This answer was edited.

    To begin with, lets us understand what the Companies Act 2013 tells about calls-in-advance, so basically as per section 50 of the companies act 2013 "A company may if so authorized by its articles, accepts from any members the whole or part of amount remaining unpaid on any share held by him, even iRead more

    To begin with, lets us understand what the Companies Act 2013 tells about calls-in-advance, so basically as per section 50 of the companies act 2013 “A company may if so authorized by its articles, accepts from any members the whole or part of amount remaining unpaid on any share held by him, even if no amount has been called up”.

    To be more precise whenever excess money is received by the company than, what has been called up is known as calls-in-advance.

    Accounting Treatment

    Well, it is to be noted that calls-in-advance is never a part of share capital. A company when authorized by its article can accept those advance amounts and directly credit the amount received to the calls-in-advance account.

    As these advance amounts are a liability for the company these are shown under the head current liability of the balance sheet until calls are made and are paid to the shareholders.

    Since this is the liability of the company, it is liable to pay the interest amount on such call money from the date of receipt until the payment is done to the shareholders. The rate of interest is mentioned in the articles of association. If the article is silent regarding the rate on which interest is paid then it is assumed to be @6%.

    Accounting Entry
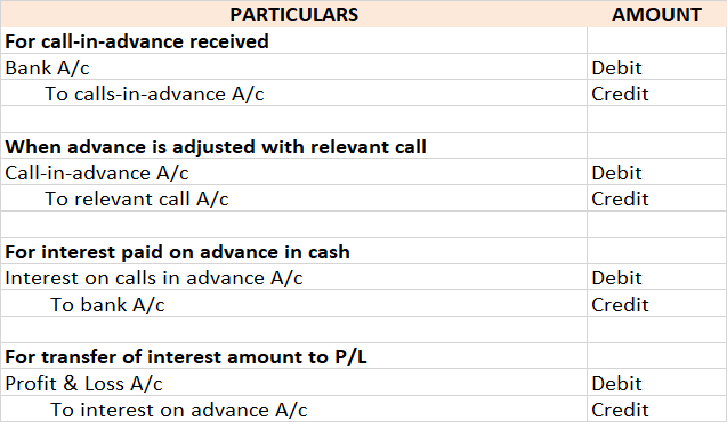
    Bonnie let us understand the entries with help of an example

    ADIDAS LTD issued 25,000 equity shares of Rs 10 each payable as follows:

    ON APPLICATION  Rs 5

    ON ALLOTMENT    Rs 3

    ON FINAL CALL     Rs 2

    Application on 30,000 shares was received. excess money received on the application was refunded immediately. Mr. X who was allotted 1,000 shares paid the call money at the time of allotment and all amounts were duly received assume interest rate @6% for 3 months, so the relevant accounting entry goes as follows:
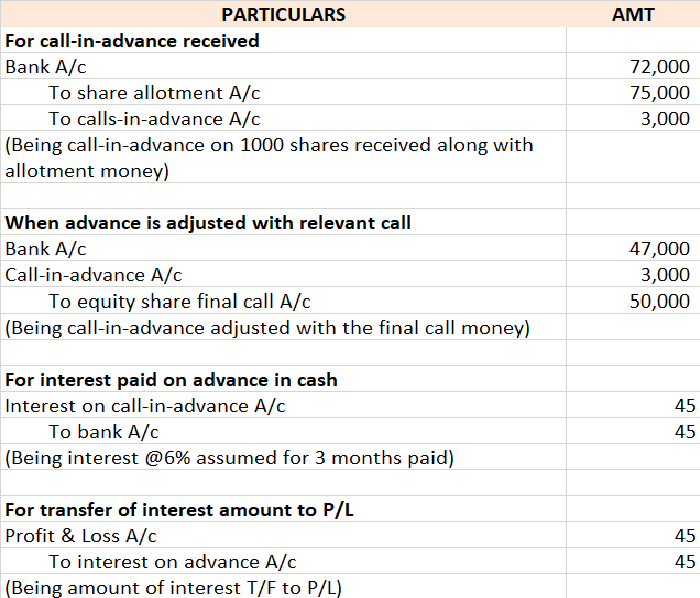
    Important Points to be noted under calls-in-advance as per the companies act 2013

    • The shareholder is not entitled to any voting rights on money paid until the said money is called for.
    • No dividends are payable on advance money.
    • Board may pay interest on advance not exceeding 12%.
    • The shareholders are entitled to claim the interest amount as mentioned in the article, if there are no profits, then it must be paid out of capital because shareholders become the creditors of the company.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Vijay
VijayCurious
In: 1. Financial Accounting > Depreciation & Amortization

Explain with rates furniture and fixtures depreciation.

  • 1 Answer
  • 0 Followers
Answer
  1. Simerpreet Helpful CMA Inter qualified
    Added an answer on July 23, 2021 at 3:29 pm
    This answer was edited.

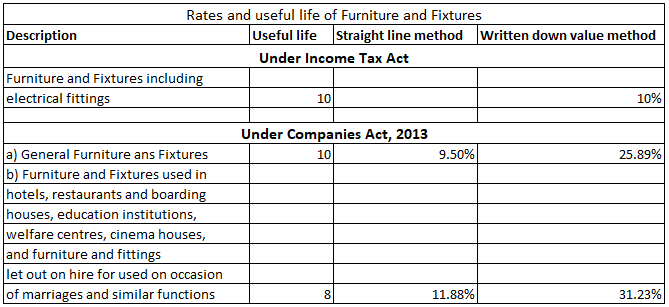
    The Furniture and Fixture is depreciated @10% according to the income tax act and as per the companies act, 2013 @9.50% under Straight line method and @25.89% under written down value method. Furniture and fixture form a major part to furnish an office. For Example, the chair, table, bookshelves, etRead more

    The Furniture and Fixture is depreciated @10% according to the income tax act and as per the companies act, 2013 @9.50% under Straight line method and @25.89% under written down value method.

    Furniture and fixture form a major part to furnish an office. For Example, the chair, table, bookshelves, etc. all comes under Furniture and Fixture. The useful life of Furniture and Fixtures is estimated as 5-10 years depending upon the kind of furniture.

    Rate of depreciation in reference to days

    • If Furniture is bought and put to use for more than 180 days, then the full rate of depreciation will be charged.
    • If the furniture is bought and put to use for less than 180 days, then half the rate of depreciation will be charged.
    • If the furniture is bought but is not put to use, then no depreciation will be charged.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Jasmeet_Sethi
Jasmeet_SethiCurious
In: 1. Financial Accounting > Ledger & Trial Balance

Main objective of preparing ledger account is to?

To ascertain the debtors and creditors of the business To ascertain the financial position of the business To ascertain the profit or loss of the business To ascertain the collective effect of all ...

  • 1 Answer
  • 0 Followers
Answer
  1. Manvi Pursuing ACCA
    Added an answer on August 11, 2021 at 9:12 am
    This answer was edited.

    The correct answer is 4. To ascertain the collective effect of all transactions pertaining to a particular account. The reason being is that in the ledger account all the effects are recorded for example,  how much money is spent on a particular type of expense or how much money is receivable from aRead more

    The correct answer is 4. To ascertain the collective effect of all transactions pertaining to a particular account. The reason being is that in the ledger account all the effects are recorded for example,  how much money is spent on a particular type of expense or how much money is receivable from a debtor. In ledger accounts, information can be obtained about a particular account.

    Ledger is the Principal book of accounts and also called the book of final entry. It summarises all types of accounts whether it is an Asset A/c, Liability A/c, Income A/c, or Expense A/c. The transactions recorded in the Journal/Subsidiary books are transferred to the respective ledger accounts opened.


    Importance of preparing ledger accounts:

    1. Ledger accounts get the ready results i.e. helps in identifying the amount payable or receivable.
    2. It is necessary for the preparation of the Trial Balance.
    3. The financial position of the business is easily available with the help of Assets A/c and Liabilities A/c.
    4. It helps in preparing various types of income statements on the basis of balances shown in ledger accounts.
    5. It can be used as a control tool as it shows balances of various accounts.
    6. It is useful for the management to forecast or plan for the future.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Manvi
Manvi
In: 1. Financial Accounting > Partnerships

Can someone show profit and loss appropriation account example?

  • 1 Answer
  • 0 Followers
Answer
  1. Ayushi Curious Pursuing CA
    Added an answer on October 21, 2021 at 7:37 pm
    This answer was edited.

    The profit and loss appropriation account is an account created in addition to the Trading & Profit and loss account in the case of partnership firms. It is a nominal account. The net profit or loss from the Profit and loss account is transferred to the Capital A/c when we do the accounting of sRead more

    The profit and loss appropriation account is an account created in addition to the Trading & Profit and loss account in the case of partnership firms. It is a nominal account.

    The net profit or loss from the Profit and loss account is transferred to the Capital A/c when we do the accounting of sole proprietors.

    But, while doing the accounting of partnership, there is a need to appropriate this profit or loss as there are two or more partners’ capital accounts. So, for this purpose, the Profit and loss appropriation account is created.

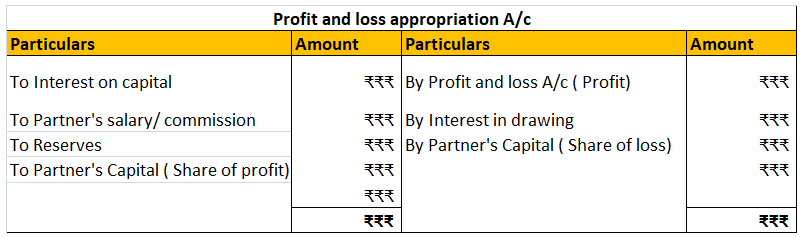
    The net profit or loss is appropriated among the partner’s capital after adjustment the items like partner’s salary, commission, interest on capital, interest on drawing etc. It consists of items related to the partner’s claim.

    The format of the profit and loss appropriation account is as below:

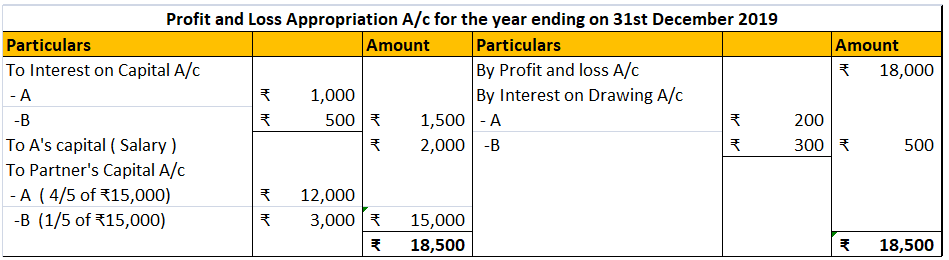
    Let solve a problem to sharpen our concept:

    A and B are partners in firm sharing profits and losses in the ratio of 4:1. On 1st January 2019, their capitals were ₹ 20,000 and ₹ 10,000 respectively. The partnership deed specifies the following:

    1. Interest on capital is to be allowed at 5% per annum.
    2. Interest on drawings charged to A and B are ₹ 200 and ₹ 300 respectively.
    3. The net profit of the firm before considering interest on capital and interest on drawings amounted to ₹ 18,000.
    4. A is to be paid an annual salary of ₹2000

    Prepare Profit and loss appropriation account for the year ending 31st December 2019.

    Solution:

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Rahul_Jose
Rahul_Jose
In: 1. Financial Accounting > Ratios

What is Statutory Liquidity Ratio?

  • 1 Answer
  • 0 Followers
Answer
  1. Pooja_Parikh Aspiring Chartered Accountant
    Added an answer on November 29, 2021 at 8:30 pm

    Statutory Liquidity ratio is the minimum percentage of reserves of liquid assets that the commercial bank should maintain. These liquid assets are in the form of gold, cash, and other securities. These reserves are kept with the bank itself and not with the Reserve Bank of India. The bank holds variRead more

    Statutory Liquidity ratio is the minimum percentage of reserves of liquid assets that the commercial bank should maintain. These liquid assets are in the form of gold, cash, and other securities. These reserves are kept with the bank itself and not with the Reserve Bank of India.

    The bank holds various demand and time deposits of the public, the total of which is called Net Demand and Time Liabilities (NDTL). This includes demand deposits that have to be paid on demand. Various other deposits like time deposits, fixed deposits, demand drafts, etc. are also included.

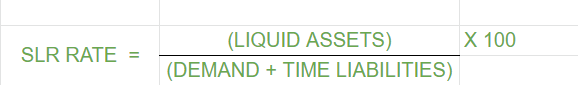
    Every bank must keep a portion of its NDTL in the form of cash, gold, or other liquid assets. Therefore, the Statutory Liquidity Ratio is the ratio of these liquid assets to the total demand and time liabilities. The authority to determine the ratio lies with the RBI, who can increase it to the extent of 40%.

    FORMULA

    PURPOSE OF SLR

    RBI controls the flow of cash in the economy by means of monetary policy measures through financial instruments like Statutory Liquidity Ratio. At the time of inflation, RBI increases SLR to reduce the flow of cash whereas, at the time of deflation, they reduce SLR to increase the flow of cash. Maintaining SLR also helps ensure the solvency of the commercial banks.

    If the banks do not maintain the necessary level of SLR, they would be liable to pay a penalty to RBI at 3% per annum above the bank rate, on the shortfall amount of that day.


    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Bonnie
BonnieCurious
In: 1. Financial Accounting > Financial Statements

How to show format of balance sheet as per companies act 2013?

  • 1 Answer
  • 0 Followers
Answer
  1. Rahul_Jose Aspiring CA currently doing Bcom
    Added an answer on December 14, 2021 at 7:08 pm
    This answer was edited.

    A balance sheet of a company is a financial statement that depicts the assets, liabilities and shareholders’ equity of the company at a point of time, usually at the end of the accounting year. A balance sheet of a company is reported in a vertical format which is different from that of a partnershiRead more

    A balance sheet of a company is a financial statement that depicts the assets, liabilities and shareholders’ equity of the company at a point of time, usually at the end of the accounting year. A balance sheet of a company is reported in a vertical format which is different from that of a partnership where the horizontal format is used.

    COMPONENTS OF A BALANCE SHEET

    The three main components of a balance sheet are Assets, Liabilities and Shareholders’ equity.

    • Assets: They are divided into two main categories that are current assets and non-current assets. If an asset is expected to be realised within 12 months or is primarily held for being traded, or is cash or cash equivalent, then those assets are termed as current assets. All assets that are not current assets are grouped under non-current assets. They are normally realised after 12 months.
    • Liabilities: They are categorised as current liabilities and non-current liabilities. If the amount owed by the company to an outside party is due to be settled in 12 months, then it can be termed as a current liability. The rest of the liabilities are referred to as non-current liability.
    • Shareholders’ Equity: This is the money owed to the owners of the company, that is shareholders. It is also called net assets since it is equal to the difference between total assets and total liabilities. Their main categories are Shareholders’ Capital and Reserves and Surplus.

    FORMAT OF BALANCE SHEET

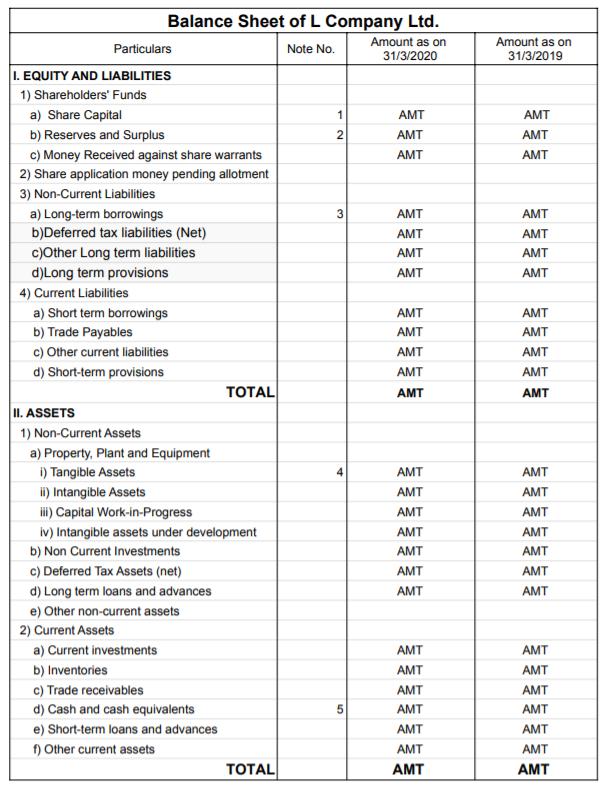
    As per the Companies Act 2013, the following format should be used for preparing a balance sheet.

    From the above Balance sheet, we should get:

    Assets = Liabilities + Shareholders’ Equity

    Relevant notes for each component should also be prepared when necessary.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
Jasmeet_Sethi
Jasmeet_SethiCurious
In: 1. Financial Accounting > Accounting Terms & Basics

What is permanent working capital?

  • 1 Answer
  • 0 Followers
Answer
  1. AishwaryaMunot
    Added an answer on July 16, 2022 at 7:30 pm

    Meaning of Working Capital Firstly, let’s understand the meaning of the working capital. Working capital is the factor which demonstrates the liquidity position of the business to carry out day to day operations. It majorly includes cash & bank balances and liquid assets. Managing working capitaRead more

    Meaning of Working Capital

    Firstly, let’s understand the meaning of the working capital. Working capital is the factor which demonstrates the liquidity position of the business to carry out day to day operations. It majorly includes cash & bank balances and liquid assets.

    Managing working capital is a crucial process to maintain short term liquidity and so ultimately resulting into achieving long term objectives efficiently. Working capital can be calculated by deducting business’s current liabilities from current assets.

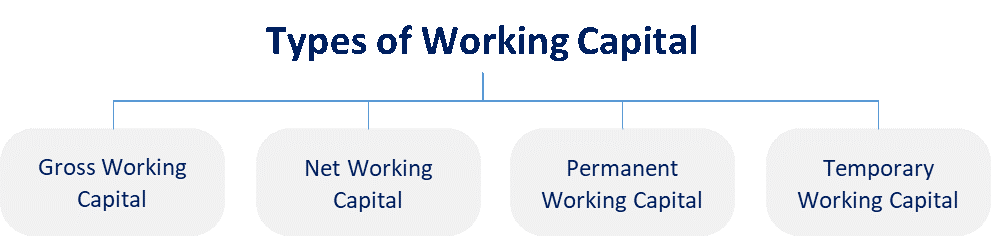
    To achieve the ideal working capital requirement for any business, it is important to understand various types of working capital and various ways to manage it.

    Coming to Permanent Working Capital, also called as Fixed Working Capital, it is the minimum working capital required or maintained by businesses. Such type of working capital is maintained to take care of regular financial obligations like creditors, inventory, salaries etc.

    Irrespective of scale of operations carried out in business, Permanent Capital is maintained by businesses which can be in form of Net Working Capital.

    There is no specific formula for calculating Fixed Working Capital, it completely depends upon the business’s assets and liabilities. So accordingly, it can be estimated through the balance sheet of the business.

    For calculating Permanent Working Capital, you can follow below steps:

    1. Calculate Net Working Capital for each day for a whole month
    2. Find the smallest value among them
    3. That will be Permanent Working Capital for the month
    4. Follow the above steps for every month
    5. There you have the annual figure for Permanent Working Capital

    The requirement of Permanent Working Capital changes as the business expands. It is crucial to make sure that the working capital level does not fall below the Permanent Working Capital requirement.

    Types of Permanent Working Capital:

    Permanent working capital is further divided into two types:

    1. Regular working capital – This refers to capital required to maintain healthy cashflow for purchases of raw materials, payment of wages etc.
    2. Reserve working capital – This refers to amount which is more than regular working capital to take care of unexpected business expenses due to contingent events.
    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
AbhishekBatabyal
AbhishekBatabyalHelpful
In: 1. Financial Accounting > Financial Statements

Where is land on a balance sheet?

  • 1 Answer
  • 0 Followers
Answer
  1. ShreyaSharma none
    Added an answer on August 19, 2022 at 8:30 pm
    This answer was edited.

    Land in the balance sheet The land is an asset and hence it is shown on the asset side of the balance sheet. On the asset side of the balance sheet, the land is stated under the heading long-term assets. Balance Sheet (for the year…) Explanation The land is a fixed asset and is supposed not to be caRead more

    Land in the balance sheet

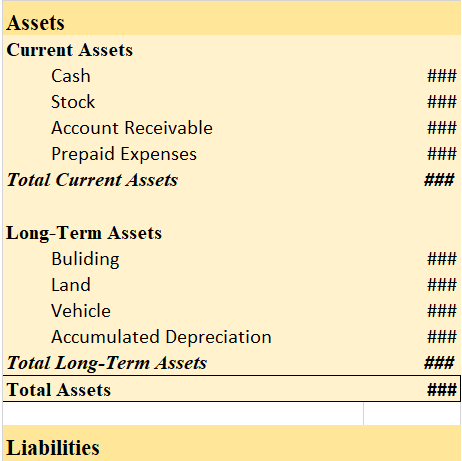
    The land is an asset and hence it is shown on the asset side of the balance sheet.

    On the asset side of the balance sheet, the land is stated under the heading long-term assets.

    Balance Sheet (for the year…)

    Explanation

    The land is a fixed asset and is supposed not to be cashed, consumed, last, sold, or written off within one accounting year and is purchased for long-term use. The fixed assets are also called non-current assets and the reason behind it is that current assets are easily converted into cash within one year and they are not.

    • The sole purpose of buying fixed assets like the land is that they are planned to be used for the long term in order to generate income.
    • Examples of fixed assets – Land, buildings, furniture, plants & equipment, etc.
    • Also called non-current assets and capital assets.


    Why is it shown on the asset side?

    The land is an asset, although it is not depreciable it is still considered to be an asset because just like other assets the business spends its own money to acquire it, and it gives them a long-term benefit while reselling it.

    Therefore, the land is shown on the asset side under the fixed asset heading.

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp
A_Team
A_Team
In: 1. Financial Accounting > Miscellaneous

Are prepaid expenses an asset?

  • 1 Answer
  • 0 Followers
Answer
  1. SidharthBadlani CA Inter Student
    Added an answer on January 6, 2023 at 8:26 am
    This answer was edited.

    Prepaid expense means a service to be rendered in the future period for which the business has already paid the remuneration. Prepaid expenses are classified as assets. The benefits of this payment will accrue to the business at a later period.  For example, insurance is often paid for annually on tRead more

    Prepaid expense means a service to be rendered in the future period for which the business has already paid the remuneration. Prepaid expenses are classified as assets. The benefits of this payment will accrue to the business at a later period. 

    For example, insurance is often paid for annually on the basis of the calendar year. A business may pay insurance every year on 1st January for that entire year. While preparing the financial statements on 31st March, it will recognize the insurance premium for the period 1st April to 31st December of the next financial year as a prepaid insurance expense. 

    Why are prepaid expenses classified as assets? 

    First of all, let us understand what an asset is. An asset is anything over which the business has ownership rights and which it can sell for money. The benefits of this asset should accrue to the business. 

    In light of this definition, let us analyze prepaid expenses as an asset. As the business has already paid for these goods or services, it becomes a legal right of the business to receive the relevant goods or services at a later date. As the benefit of this expense would accrue to the business only at a later date, the prepaid expenses are classified as an asset. 

    Some examples of prepaid expenses are prepaid insurance, prepaid rent etc

    Treatment of Prepaid Expenses

    Prepaid expenses are recorded in the balance sheet under the heading “Current Assets” and sub-heading “Other Current Assets”

    As per the Generally Accepted Accounting Principles or GAAP, expenses must be recognized in the accounting period to which they relate or in which the benefit due to them is likely to arise. Thus, we cannot recognize the prepaid expenses in the accounting period in which they are incurred. 

    Prepaid assets are classified as assets and carried forward in the balance sheet to be debited in the income statement of the accounting period to which they relate. 

    Adjusting Entries

    Adjusting entries are those entries that are used to recognize prepaid expenses in the income statement of the period to which they relate. These entries are not used to record new transactions. They ensure compliance with GAAP by recognizing the expenses in the period to which they relate. 

    Conclusion

    The GAAP and basic definition of an asset govern the treatment of prepaid expenses as an asset. The business incurs them in an accounting period different from the accounting period in which their benefit would accrue to the business. The business has a legal right to receive those goods or services. 

    The business carries them as a current asset on the balance sheet. In the relevant accounting period, they are recognized in the income statement. 

    See less
    • 0
    • Share
      Share
      • Share on Facebook
      • Share on Twitter
      • Share on LinkedIn
      • Share on WhatsApp

Sidebar

Question Categories

  • 1. Financial Accounting

      • Accounting Terms & Basics
      • Bank Reconciliation Statement
      • Banks & NBFCs
      • Bills of Exchange
      • Capital & Revenue Expenses
      • Consignment & Hire Purchase
      • Consolidation
      • Contingent Liabilities & Assets
      • Departments & Branches
      • Depreciation & Amortization
      • Financial Statements
      • Goodwill
      • Insurance Accounting
      • Inventory or Stock
      • Investment Accounting
      • Journal Entries
      • Ledger & Trial Balance
      • Liquidation & Amalgamation
      • Miscellaneous
      • Not for Profit Organizations
      • Partnerships
      • Ratios
      • Shares & Debentures
      • Source Documents & Vouchers
      • Subsidiary Books
  • 2. Accounting Standards

      • AS
      • IFRS
      • IndAS
  • 3. Cost & Mgmt Accounting
  • 4. Taxes & Duties

      • GST
      • Income Tax
  • 5. Audit

      • Bank Audit
      • Internal Audit
      • Miscellaneous - Audit
      • Statutory Audit
  • 6. Software & ERPs

      • Tally
  • 7. MS-Excel
  • 8. Interview & Career
  • Top Questions
  • I need 20 journal entries with ledger and trial balance?

  • Can you show 15 transactions with their journal entries, ledger, ...

  • What is furniture purchased for office use journal entry?

  • What is loose tools account and treatment in final accounts?

  • What is the Journal Entry for Closing Stock?

  • What is the journal entry for goods purchased by cheque?

  • What is commission earned but not received journal entry?

  • How to show adjustment of loose tools revalued in final ...

  • What is the journal entry for interest received from bank?

  • Following is the Receipts and Payments Account of Bharti Club ...

Hot Topics

Accounting Policies Accounting Principles Balance Sheet Bank Reconciliation Statement Bill of Exchange Branch Accounting Calls in Advance Capital Capital Expenditure Companies Act Compound Entry Consignment Creditors Current Assets Debit Balance Debtors Depreciation Difference Between Dissolution of Firm Dissolution of Partnership Drawings External Users Fictitious Assets Final Accounts Financial Statements Fixed Assets Fixed Capital Fluctuating Capital Gain Impairment Installation Interest Received in Advance Internal Users Journal Entry Ledger Loose Tools Miscellaneous Expenditure Profit Rent Rent Received in Advance Reserves Revaluation Revenue Expenditure Revenue Reserve Sacrificing Ratio Subscription Subscription Received in Advance Trial Balance Type of Account Uncalled Capital
  • Home
  • Questions
    • Most Visited
    • Most Active
    • Trending
    • Recent
  • Follow
    • Categories
    • Users
    • Tags
  • Write an Answer
  • Badges & Points
  • Request New Category
  • Send a Suggestion

Most Helping Users

Astha

Astha

  • 50,291 Points
Leader
Simerpreet

Simerpreet

  • 72 Points
Helpful
AbhishekBatabyal

AbhishekBatabyal

  • 65 Points
Helpful

Footer

  • About Us
  • Contact Us
  • Pricing
  • Refund
  • Forum Rules & FAQs
  • Terms and Conditions
  • Privacy Policy
  • Career

© 2021 All Rights Reserved
Accounting Capital.