

Current assets are all the assets of the company which are expected to be used, sold, or consumed within one year. Current assets are those assets that can be converted into cash easily. For example - Inventory, Accounts Receivable, Cash, and Cash Equivalents. Loose tools are parts of machinery or sRead more
Current assets are all the assets of the company which are expected to be used, sold, or consumed within one year. Current assets are those assets that can be converted into cash easily.
For example – Inventory, Accounts Receivable, Cash, and Cash Equivalents.
Loose tools are parts of machinery or spare parts of machinery. Loose can be classified on the nature of use whether it is a fixed asset or a current asset. If loose tools are used regularly or within one accounting year, it is classified as a current asset.
Loose tools are usually classified as a current asset, however, there is one exception i.e it is excluded from the current ratio.
They are excluded from the current ratio because the current ratio takes into account only current assets, and the nature of loose tools is either a fixed asset or a current asset and can’t be converted into cash easily.
The current ratio is calculated to check the liquidity of the company.
Loose tools appear in the Asset Side of the Balance Sheet under the head Current Asset, subhead Inventories.
The extract of the Balance Sheet is as follows:
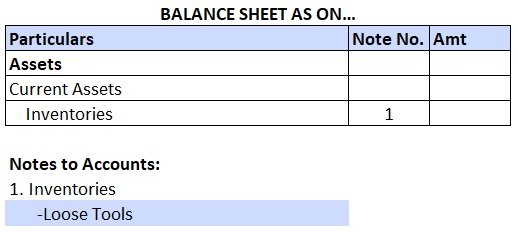
When the balance sheet prepared under Schedule III loose tools is shown under notes to accounts under sub-head Inventories on the asset side.
When the balance sheet is in a T format loose appears as a current asset after recording fixed assets on the asset side.
See less







Definition Gross profit is the excess of the proceeds of goods and services rendered during a period over their cost, before taking into account administration, selling, distribution, and financial expenses. Gross profit and net profit are gross profit estimates of the profitability of a company. WhRead more
Definition
Gross profit is the excess of the proceeds of goods and services rendered during a period over their cost, before taking into account administration, selling, distribution, and financial expenses.
Gross profit and net profit are gross profit estimates of the profitability of a company.
When the result of this computation is negative it is referred to as gross loss
Formula :
Total Revenues – Cost Of Goods Sold
Net profit is defined as the excess of revenues over expenses during a particular period.
Net profit is to show the performance of the company.
When the result of this computation is negative it is called a net loss.
Net profit may be shown before or after tax.
Formula :
Total Revenues – Expenses
Or
Total Revenues – Total Cost ( Implicit And Explicit Cost )
Examples
Now let me explain to you by taking an example which is as follows :
In a business organization there were the following data given as purchases made Rs 73000, inventory, in the beginning, was Rs 10000, direct expenses made were Rs 7000, closing inventory which was Rs 5000, revenue from operation during the period was Rs 100000.
Then,
COST OF GOODS SOLD = Purchases + Opening Inventory + Direct Expenses – Closing Inventory.
= Rs ( 73000 + 10000+ 7000- 5000)
= Rs 85000
GROSS PROFIT = REVENUE – COST OF GOODS SOLD
= Rs ( 100000 – 85000 )
= Rs 15000
Now from the above question keeping the gross profit same if the indirect expenses of the organization are Rs 2000 and the other income is Rs 1000.
Then,
NET PROFIT = GROSS PROFIT – INDIRECT EXPENSES + OTHER INCOMES
= Rs ( 15000 – 2000 + 1000)
= Rs 14000
Treatment
Treatment of gross profit and net profit is given as follows :
Gross profit
• Gross profit appears on the credit side of the trading account.
• Gross profit is located in the upper portion beneath revenue and cost of goods sold.
Net profit
• Net profit appears on the credit side of the profit and loss account.
• It is treated directly in the balance sheet by adding or subtracting from the capital.
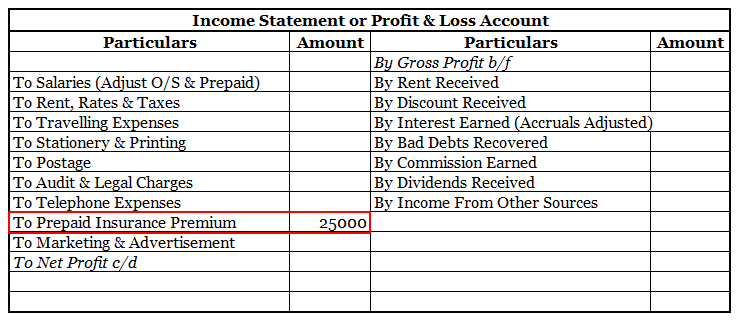
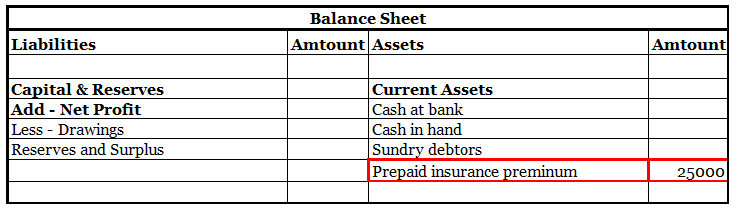
Here is an extract of the trading and profit/loss account and balance sheet showing GROSS PROFIT & NET PROFIT :

See less