

Bad debts mean the money owed by customers who have gone bankrupt or the likelihood of who's ever returning the money is significantly low. Bad debt is a nominal account. A nominal account is an account that records the business transactions belonging to a certain category of income, expense, profitRead more
Bad debts mean the money owed by customers who have gone bankrupt or the likelihood of who’s ever returning the money is significantly low. Bad debt is a nominal account.
A nominal account is an account that records the business transactions belonging to a certain category of income, expense, profit or loss. The balances on nominal accounts are normally written off at the end of each financial year. For example, sales A/c, purchases A/c, interest income, loss from the sale of assets etc.
Why are bad debts A/c classified as a nominal account?
First of all, let us understand the other two types of accounts – personal accounts and real accounts.
Personal accounts deal with the records of the business’ transactions with a particular person or entity. For example Mukesh A/c, Mahesh A/c, Reliance A/c, Suresh and Co. A/c etc.
Real accounts deal with transactions and records related to assets. The balance in these accounts is normally carried forward from one period to another. For example “Furniture A/c “, ” Building A/c ” etc.
Now that we have understood the basic definitions of all three types of accounts, we can discuss the reason behind the classification of bad debts as nominal accounts.
A bad debt is a loss that the company has incurred. It may be due to bankruptcy of customers, customer fraud etc. The company isn’t going to receive that money. The bad debts are written off at the end of the year by transferring them to profit and loss A/c.
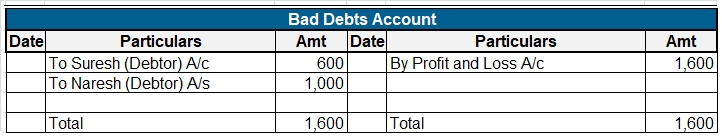
Thus, bad debts relate to loss and are normally not carried forward from one period to another. Hence, they are classified as nominal accounts.
Treatment of Bad Debts
Bad debts are written off at the end of each year by debiting them to the profit and loss A/c. The amount of bad debts is reduced from the amount of debtors that the company has.
A company may also choose to create a provision for bad debts for the balance amount of debtors that the company has after adjusting for bad debts. This provision represents a rough estimate of the amount due to debtors that the business expects to not receive. In other words, it is an estimate of customer bankruptcy that the business expects.
Conclusion
We can conclude that
- There are primarily three types of accounts – real, personal and nominal.
- Bad debts are a nominal account.
- Bad debts is a loss that the business has incurred
- It may be due to bankruptcy of customers, fraud etc
- Bad debts are written off each year by transferring them to the income statement









Fictitious assets are the expenses and losses which are yet to be written off, so they appear in the Asset side of the balance sheet of the relevant financial year because expenses and losses have a debit balance. They are not assets in substance. Examples: Business loss ( debit balance of Profit anRead more
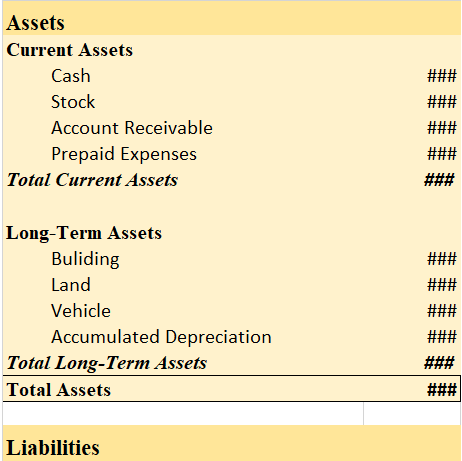
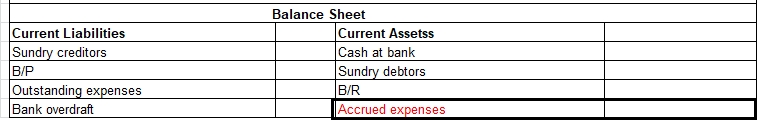
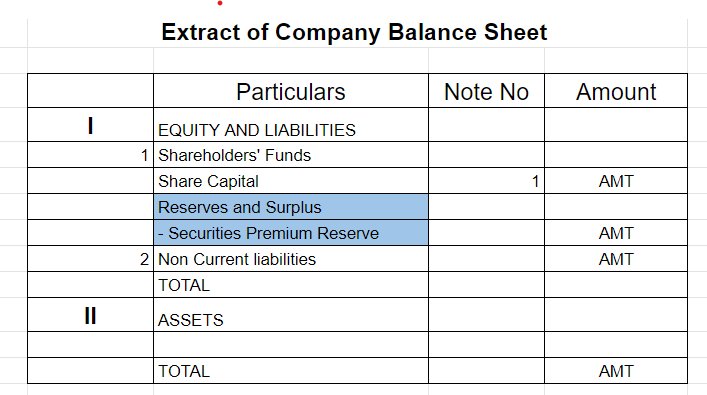
Fictitious assets are the expenses and losses which are yet to be written off, so they appear in the Asset side of the balance sheet of the relevant financial year because expenses and losses have a debit balance. They are not assets in substance.
Examples:
*business loss is shown as a negative figure under the head Reserve and Surplus, when the balance sheet is prepared as per Schedule III of The Companies Act, 2013.
Deferred revenue expenditures are the expenses incurred for which the benefits are expected to flow to the enterprise beyond the current year. Such expenses are huge and are not written off completely in a financial year. The part of the expenditure which is not written off is shown on the assets side of the balance sheet.
Examples:
As you can see, there is some similarity between the two. Deferred revenue expenditure can be called a type of fictitious asset as it is shown in the asset side of the balance sheet but it isn’t an asset.
The term ‘fictitious asset’ has a broader meaning than deferred revenue expenditure and also includes the losses such as discounts on the issue of debenture and business loss.
The difference between fictitious assets and deferred revenue expenditure are as follows: