

Journal entry for goods purchased by cheque The journal entry for goods purchased by cheque is as follows: In this journal entry, purchase account and bank account are involved. The explanation is given below. Explanation Purchase Whenever there is a purchase of goods, the purchase account is debiteRead more
Journal entry for goods purchased by cheque
The journal entry for goods purchased by cheque is as follows:
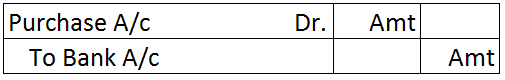
In this journal entry, purchase account and bank account are involved. The explanation is given below.
Explanation
Purchase
Whenever there is a purchase of goods, the purchase account is debited.
Goods refer to the items which an enterprise manufactures or purchases and sells to generate its business revenue.
If there is a purchase of any other item which does not satisfy the above definition of goods, then the purchase account is not involved.
For example, if stationery is purchased and the enterprise does not trade in stationery items, then the purchase account will not appear in the journal entry.
Payment by cheque
Payment by cheque means the payment amount will be deducted from the bank account balance. Hence, in the given journal entry, the bank account is involved.
The logic behind the debit and credit
The golden rules of accounting
Purchase is an expense hence it is a nominal account. The golden rule for nominal accounts is “Debit all expense and loss and credit all incomes and gains”
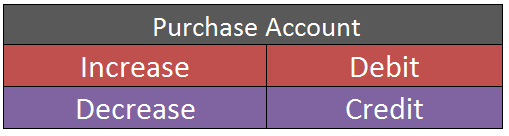
Hence, the purchase account is debited.
Bank is a real account and the golden rule of accounting for real accounts is, “Debit what comes in, credit what goes out”.
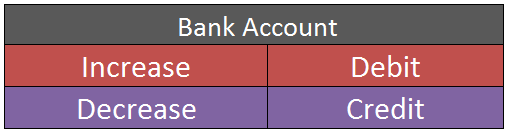
Hence, the bank account is credited as money is going out of the bank.
Modern rules of accounting
Purchase is an expense account, and expenses are debited when increased and credited when decreased.
Hence, the purchase account is debited here.
A bank account is an asset account. Asset accounts are debited in case of an increase and credited in case of a decrease. Hence, the bank account is credited here.
See less











The value of inventory at the end of the financial year or balance sheet date is called closing stock. Closing stock includes: Raw Material Work-in-Progress Finished Goods Example: If the value of raw material is Rs 10,000, value of WIP is Rs 5,000 and value of Finished Goods is Rs 15,000 then valueRead more
The value of inventory at the end of the financial year or balance sheet date is called closing stock. Closing stock includes:
Example:
If the value of raw material is Rs 10,000, value of WIP is Rs 5,000 and value of Finished Goods is Rs 15,000 then value of Closing Stock will be Rs (10,000 + 5,000 + 15,000) = Rs 30,000
Adjustment entries are done on the accrual basis of accounting, that is, income is recorded when earned and not received and expenses are recorded when incurred and not paid. Adjustment entries are usually made before or after the preparation of the trial balance at the end of the accounting period.
If the entries are made after the preparation of the trial balance, then two adjustment entries are recorded while preparing Trading and Profit & Loss A/c.
Since closing stock is an item outside the trial balance, the double-entry would be:
The journal entry
The second adjustment would be to show closing stock on the balance sheet and since the closing stock is an asset it is shown under the head Current Assets.
In case where adjustment for Closing Stock is to be done before preparation of Trial Balance, then it will be shown on the credit side of the Trial Balance, since it is an asset for the company and will have a credit brought down balance as shown in the image.
Later, while preparing Balance Sheet, Closing Stock will be shown on the Asset side of the Balance Sheet.
See less