

Ledger posting As we know, a business records all of its transactions in the journal. After the transactions are recorded in the journal, they are posted in the principal book called ‘Ledger’. Transferring the entries from journals to respective ledger accounts is called ledger posting or posting toRead more
Ledger posting
As we know, a business records all of its transactions in the journal. After the transactions are recorded in the journal, they are posted in the principal book called ‘Ledger’. Transferring the entries from journals to respective ledger accounts is called ledger posting or posting to the ledger accounts. Balancing of ledgers is carried out to find differences at the year’s end.
Posting to the ledger account means entering information in the ledger, and respective accounts from the journal for individual records. The accounts that are credited are posted to the credit side and vice versa.
Ledger maintenance is done at the end of an accounting period and it’s maintained to reflect a permanent summary of all the journal accounts. In the end, all the accounts that are entered and operated in the ledger are closed, totaled, and balanced. Balancing the ledger means finding the difference between the debit and credit amounts of a particular account.
While posting to the ledger account, suppose goods were bought for cash. While passing the journal entry, we’ll be debiting the purchases a/c and crediting the cash a/c by stating it as, ‘To Cash A/c’.
Now, this entry will be affecting both the purchases account and the cash account. In the cash account, we’ll be debiting purchases. Whereas in the purchases account, we’ll be crediting the cash. That’s how it works in the double-entry bookkeeping system of accounting.
Example
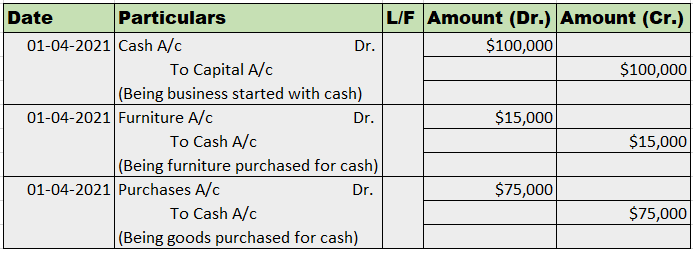
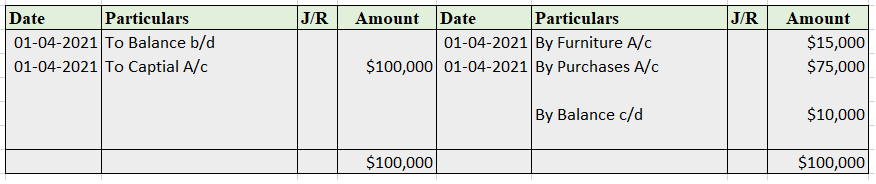
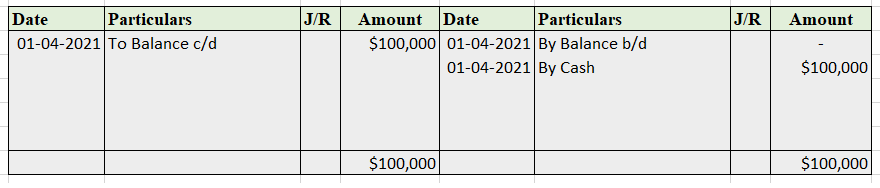
Mr. Tony Stark started the business with cash of $100,000 on April 1, 2021. He bought furniture for business for $15,000. He further purchased goods for $75,000.
Now, we’ll be journalizing the transactions and posting them into the ledger accounts.
Journal Entries
Posting to Ledger Account
Cash A/c
Capital A/c
Furniture A/c
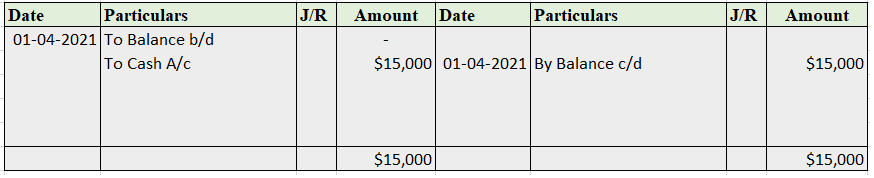
Purchases A/c
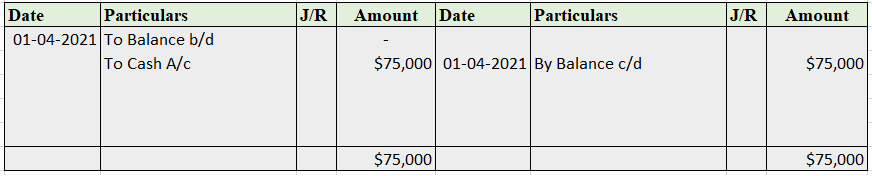
See less





Introduction Audit refers to an independent examination of the financial information of any entity to express an opinion on the financial statements of the entity. An audit is conducted to ensure that the financial statements of the entity whose books of accounts are audited reflect a true and fairRead more
Introduction
Audit refers to an independent examination of the financial information of any entity to express an opinion on the financial statements of the entity. An audit is conducted to ensure that the financial statements of the entity whose books of accounts are audited reflect a true and fair view of the affairs of the entity.
In audit reports, an auditor uses the term ‘true and fair’ is used to express that the financial statements are free from any kind of material misstatement and depict a correct financial image of the entity.
The term holds great significance in the audit reports of entities and auditors have to use this term carefully.
Meaning of ‘True’ and ‘Fair’
The term consists of two words, ‘True’ and ‘Fair’. Let’s understand what each of these words actually means.
True
The word ‘true’ suggests that the auditor, after examining the financial statements, has found no material misstatement whether due to error or fraud. The financial information depicted by the financial statements and the underlying accounting records is correct. The preparation and presentation of the financial statements are in accordance with the accounting standards applicable to the entity.
Fair
The word ‘fair’ means the financial information presented through the financial statement does not have an element of bias or sugar coating. There is a faithful presentation of financial information and the amounts at which the assets and liabilities, income and expenses and equity are shown is justified.
See less